An offshore company in the UAE is generally a company registered in a free zone or similar jurisdiction for holding assets, investments or cross-border business, and it is not a licence to trade freely in the UAE mainland. The popular advice to register offshore for automatic tax savings and unrestricted business access confuses incorporation with permissions the company must qualify for separately.
For an investor, that distinction determines whether the structure solves an ownership problem or creates an operating problem. Start with what the business needs to do, not with the offshore label or an advertised registration package.
What an Offshore Company in the UAE Really Is
An offshore company is a regulated corporate vehicle, not a category of business that sits outside ordinary compliance. Its registration establishes an entity that can undertake permitted ownership, investment or international activities. It doesn't, by itself, establish unrestricted operating rights.
Think of it as a passport for ownership, not a shop permit. A company might be suitable for holding shares in an overseas business while being unsuitable for running a customer-facing operation in Dubai. Those are different purposes, even when the same entrepreneur controls both businesses.
Registration and operating permission are different
The Dubai Airport Free Zone regulations make the boundary concrete: a company or branch must hold a valid licence, and that licence authorises operations within the free zone without itself authorising activities outside it. The framework also recognises foreign-company branches and requires accurate ultimate-beneficial-owner information.
That means offshore and free-zone aren't interchangeable descriptions of a company's capabilities. A holding vehicle and a licensed free-zone operating business may both sit outside the mainland framework, but their permitted activities can be materially different.
Offshore, free-zone and mainland structures compared
| Structure | Sells to UAE mainland customers | Typical use |
|---|---|---|
| Offshore or non-mainland holding company | Not on its own; needs an appropriate mainland licence, branch or distributor route | Holding shares, investments and assets |
| Free-zone company with activity licence | Generally needs a mainland distributor, branch or approval | Trading and operations within the free zone and abroad |
| Mainland company | Yes, with a UAE mainland licence covering the activity | Local operations, staff and local sales |
Read the table as a starting point, not as permission for a particular transaction. A distributor arrangement appropriate for goods shouldn't be assumed to authorise an unrelated service business.
Test the business before choosing the entity
Before comparing incorporation offers, prepare a short operating map:
- Customers: Identify where buyers are located and where the service or product reaches them.
- Contracts: Name the entity that will sign agreements, issue invoices and receive payment.
- Physical activity: Describe where people work, where assets sit and where delivery happens.
The useful answer to “What is an offshore company in UAE?” therefore goes beyond its place of registration. It's an entity whose usefulness depends on whether its permissions match the job you're giving it.
What an Offshore Company Can and Cannot Do
What each structure can do in the UAE
| Capability | Offshore holding company | Mainland or licensed free-zone company |
|---|---|---|
| Hold shares, investments or other assets | Yes, within permitted activities | Yes, within permitted activities |
| Invoice and sell to UAE mainland customers | No, not directly on offshore registration alone | Yes, with an appropriate mainland licence or authorised market-access route |
| Employ staff and rent premises | Generally no for local operating purposes | Yes, subject to licence, employment and premises requirements |
| Sponsor UAE residence visas | Generally no | Available subject to licensing and immigration requirements |
| Open a bank account | Not automatic; needs source-of-funds and business-purpose evidence | Subject to documents, bank checks and approval |
| Own UAE property | Only where the structure and local property rules permit | Only where the entity and property rules permit |
The UAE government's guidance on running a free-zone business distinguishes international and in-zone trade from mainland sales, which generally require a distributor, branch, company, licence or approval. A registered entity isn't automatically an authorised local supplier.
Where an ownership arrangement becomes an operating problem
Say a software founder establishes an offshore company to hold intellectual property, then uses that company to invoice Dubai customers for implementation and support. The intellectual-property ownership may fit the intended structure. The customer contracts require a separate licensing assessment.
The issue isn't the invoice template or the bank receiving payment. It's whether the contracting company is authorised to provide the promised service in the relevant market. A mainland entity, or a licensed free-zone entity with the necessary mainland route, may need to perform and invoice that work.
Keep the ownership agreement and customer agreement distinct. The IP owner can license rights under an appropriately reviewed arrangement, while the authorised operating company delivers the customer service. That division must reflect what the companies do, not merely what their contracts call them.
Our onshore versus offshore comparison is useful when deciding whether you need an ownership vehicle, an operating business or a combination.
Banking and transparency require their own evidence
Ofin Legal's UAE offshore guidance identifies a 25% ownership or control threshold in beneficial-ownership reporting and describes bank onboarding evidence such as source of funds, business purpose, ownership, contracts and expected transaction flows. Offshore incorporation therefore shouldn't be sold as anonymity or guaranteed banking.
Prepare an ownership chart that connects the company to the individuals who ultimately own or control it. Explain how they accumulated the funds being introduced, why the company exists and which counterparties will send or receive money.
Property needs a separate check, too. An entity suitable for holding overseas investments isn't automatically eligible to own a particular UAE property. Confirm eligibility for the specific structure and asset before signing a purchase agreement.
Practical rule: Match the company to the contract, the contract to the licensed activity, and the bank file to the transactions you actually expect.
Fix the avoidable mismatches
These corrections belong in the setup budget rather than being treated as administrative cleanup:
- Replace the tax-free assumption: Classify expected income and obtain a tax assessment before committing to the structure.
- Separate personal and company money: Record capital contributions, shareholder loans, expenses and distributions distinctly.
- Correct the contracting entity: Put mainland customer agreements into an entity authorised for the relevant activity.
- Maintain ownership records: Review changes in ownership and control against the applicable reporting requirements.
- Assign compliance responsibility: Give accounts, corporate tax, VAT assessment and ownership updates named owners and calendar entries.
Budget for recurring compliance, not just registration. A company that holds assets must still keep records explaining what it owns, how it was funded, and what income it receives.
Why Offshore Does Not Mean Tax-Free
The assumption that offshore means tax-free fails because tax treatment follows the entity's circumstances and income, not its marketing description. Free-zone tax treatment is conditional, and qualifying status requires evidence.
The UAE government corporate-tax guidance states that the regime applies from the beginning of a business's first financial year starting on or after 1 June 2023, with 0% on taxable income up to AED 375,000 and generally 9% above that threshold. Those are taxable-income bands, not a blanket exemption for offshore companies.
UAE corporate tax rates that apply to offshore structures
| Situation | Tax rate | Condition |
|---|---|---|
| Taxable income up to AED 375,000 | 0% | Applies under the standard Corporate Tax regime |
| Taxable income above AED 375,000 | 9% | Standard rate, subject to applicable rules and exemptions |
| Qualifying Free Zone Person | 0% on qualifying income | Meets qualifying-income, substance, transfer-pricing, audit and revenue conditions |
| Multinational group in scope of Domestic Minimum Top-up Tax | 15% effective | Applies for fiscal years beginning on or after 1 January 2025 |
The Ministry of Finance's corporate-tax framework describes the conditional 0% treatment for a Qualifying Free Zone Person and the 15% effective rate under the Domestic Minimum Top-up Tax for qualifying multinational groups for fiscal years beginning on or after 1 January 2025. The latter is a group-specific rule, not a general rate for an independent offshore holding company.
Qualifying treatment needs more than incorporation
A proposed holding company needs an income-by-income review. Dividends, licensing receipts, trading income and service fees shouldn't be grouped together under an unsupported tax-free assumption.
Management arrangements matter as well. Document who makes decisions, where relevant work happens, how related parties transact and which records demonstrate adequate substance. Audited financial statements and transfer-pricing compliance are part of the qualifying assessment, not optional presentation documents.
A tax-residency certificate is also separate from incorporation. The official cost of a UAE Tax Residency Certificate is AED 550 for an FTA-registered applicant, but paying the fee doesn't establish eligibility or guarantee treaty benefits. Residence and factual substance require their own assessment.
Prepare the tax file before applying
Our corporate tax planning guidance supports a review of the proposed structure before transactions begin. Prepare:
- Income descriptions: Explain the source, payer and commercial basis of each revenue stream.
- Accounting arrangements: Establish how transactions, assets and related-party balances will be recorded.
- Qualification evidence: Assess free-zone conditions against actual activities and management.
- VAT analysis: Review VAT separately rather than assuming the corporate-tax conclusion settles it.
The right question isn't whether the registration is offshore. It's which rules apply to the income and whether the company can prove it meets them.
How to Judge a UAE Jurisdiction Before You Apply
Choose a jurisdiction by the activities it permits, not by how prominently an incorporation package advertises offshore benefits. Your shortlist should begin with a written business description that every registration authority can assess against the same facts.
For example, “holding investments” and “selling software implementation services” aren't equivalent activity descriptions. A quote based on the former doesn't establish permission for the latter, even if both relate to the same technology business.
Compare permission before price
Use a comparison sheet rather than collecting headline registration prices. Ask the relevant authority to confirm the proposed activity, document type and operating boundary in writing.
| Decision point | Evidence to obtain | Reason to reject an option |
|---|---|---|
| Permitted purpose | Written confirmation of the holding, licensing or trading activity | The description doesn't cover the intended business |
| Customer access | Confirmation of the route for serving intended UAE customers | The proposed sales model lacks an authorised route |
| Corporate documentation | Confirmation of the certificate, licence and ownership records issued | Documents are described vaguely or permissions are overstated |
| Ongoing administration | Written breakdown of renewal and compliance responsibilities | The offer explains registration but not ongoing obligations |
| Fees | Itemised quotation identifying inclusions and exclusions | Material charges remain unexplained |
Don't treat a certificate of incorporation as an activity licence. Ask what each document proves and what separate approvals remain necessary.
Request a usable written quote
Registration charges differ by jurisdiction, so there isn't a single national offshore setup price to apply to every business. Request an itemised quote before paying, with incorporation, registered administration, renewals and optional support separated.
Also identify expenditure outside the registration package. Banking preparation, accounting, tax assessment and document formalities should be visible in the budget, whether they're included or separately arranged.
We provide company formation, offshore registration and ongoing compliance services, so the discussion can cover the entity's intended purpose rather than registration alone. Bring the proposed customer and ownership map to that discussion.
A jurisdiction is suitable only when you can explain what the company may do, which document authorises it and what remains outside its permission.
Reject an option if the authority won't clarify those boundaries in writing. A less expensive certificate doesn't compensate for choosing an entity that can't carry out the intended activity.
Who Should Use an Offshore Company
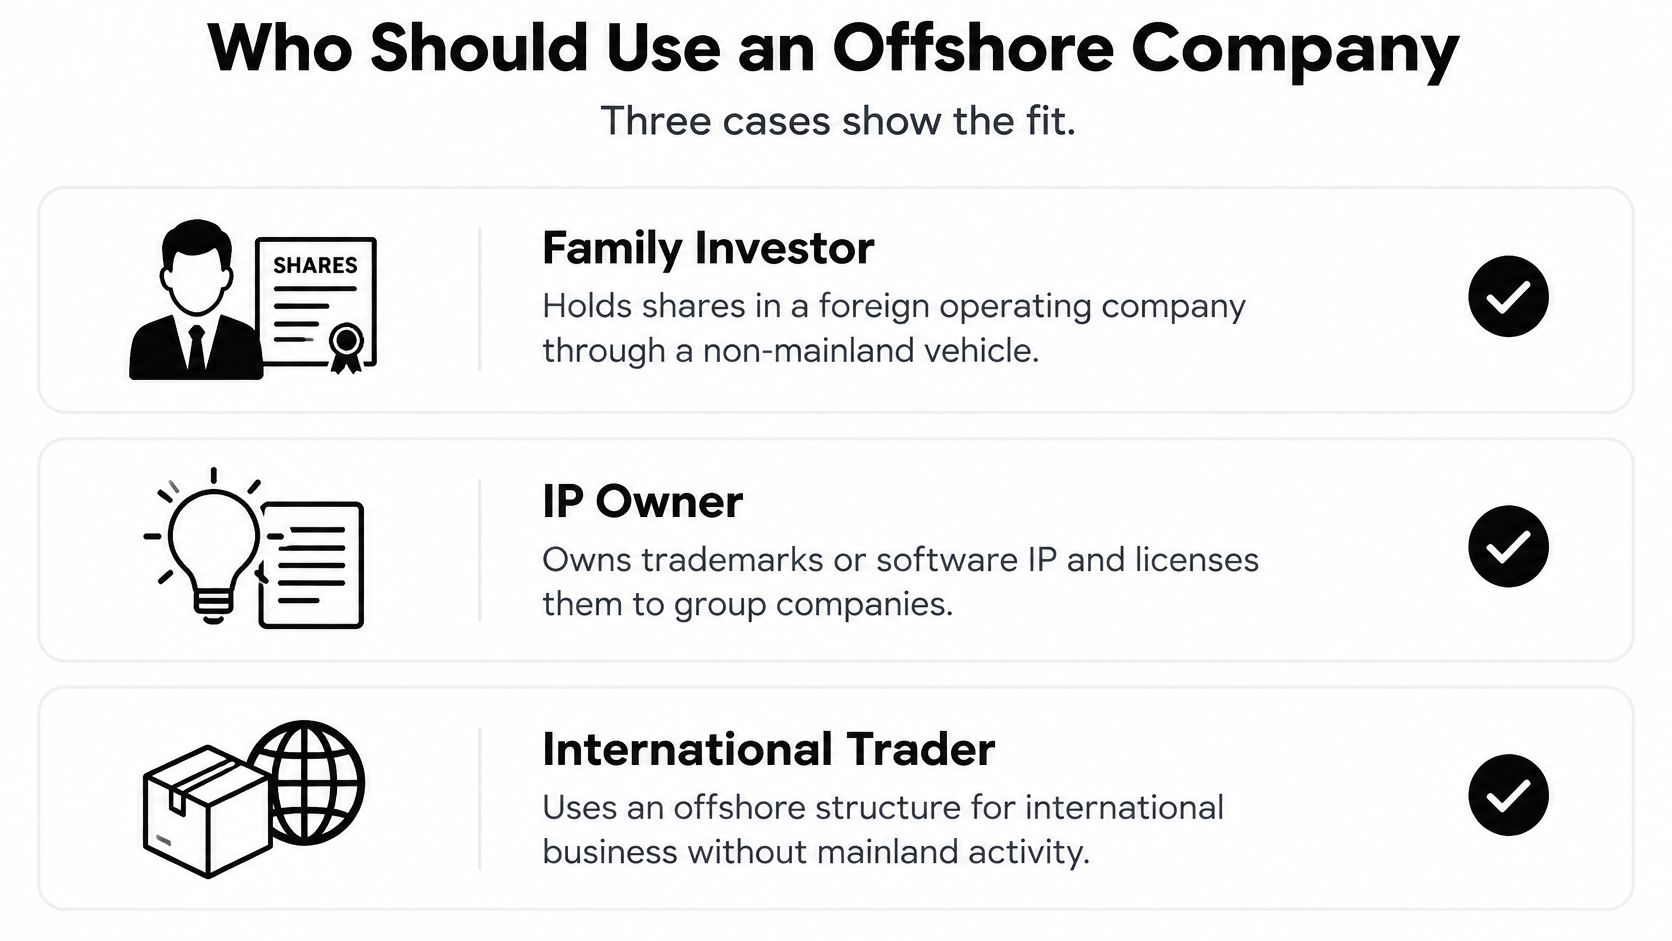
A family investor wants to hold shares in a foreign operating company through a separate corporate vehicle. The investor isn't trying to establish a Dubai sales team or deliver local services. The main question is whether the proposed entity can hold those shares and support the family's ownership arrangements.
That is a plausible offshore use because the intended job is ownership rather than local operation. It still needs an assessment of the investment's location, tax treatment, banking and the rules affecting the underlying company.
Similar assets can require different structures
Consider a founder who owns trademarks or software IP. A holding vehicle may be appropriate where its permitted purpose covers owning those rights and licensing them to group companies. The arrangement needs commercial terms, an identifiable owner and an explanation of who develops, manages and exploits the IP.
An operating software business is different. If the founder's real objective is to recruit developers, manage delivery and sell ongoing services, an ownership-only company doesn't address the whole business model. The founder should design the operating structure alongside the IP arrangement.
A property investor presents another case. A vehicle holding foreign real estate may serve an ownership objective, subject to the property's local rules and relevant tax treatment. It shouldn't be selected merely because the investor assumes a UAE entity can own property anywhere.
International traders need an equally practical distinction. A structure for permitted cross-border transactions must match the trading activity, counterparties and transaction flows. A business needing warehousing, local employees or UAE distribution should assess an operating licence rather than copying a passive investor's setup.
Decide what the company is being hired to do
Use these decision questions to separate a genuine holding requirement from an operating requirement:
- Asset ownership: Is the company's principal job to hold identifiable investments, rights or property?
- Separation of functions: Is there a commercial reason to separate ownership from the business using the assets?
- Cross-border flows: Can you explain the underlying purpose of dividends, royalties, trading receipts or investment payments?
- Local substance: Will the business need people, premises, management activity or customer delivery in the UAE?
A holding-only model points towards assessing an offshore vehicle. In-zone operations and exports point towards a licensed free-zone option. A business centred on mainland customers needs an appropriate mainland operating route.
These aren't interchangeable ways to purchase the same result. They're responses to different business requirements.
Check the expansion plan before registering
Include the intended next stage, not just the first transaction. A founder planning to add local operations should compare an operating structure now with the work required to add another entity later.
We assist investors with PRO services in Dubai and across the UAE. That support is relevant where the ownership plan must be coordinated with administrative requirements for a separately licensed business.
Before paying a registration fee, write down the assets to be held, the work to be performed and the entity responsible for each. Request a written structure review and fee quote against that description. Registering first and defining the business afterwards reverses the sensible order.
How to Set Up an Offshore Company Step by Step
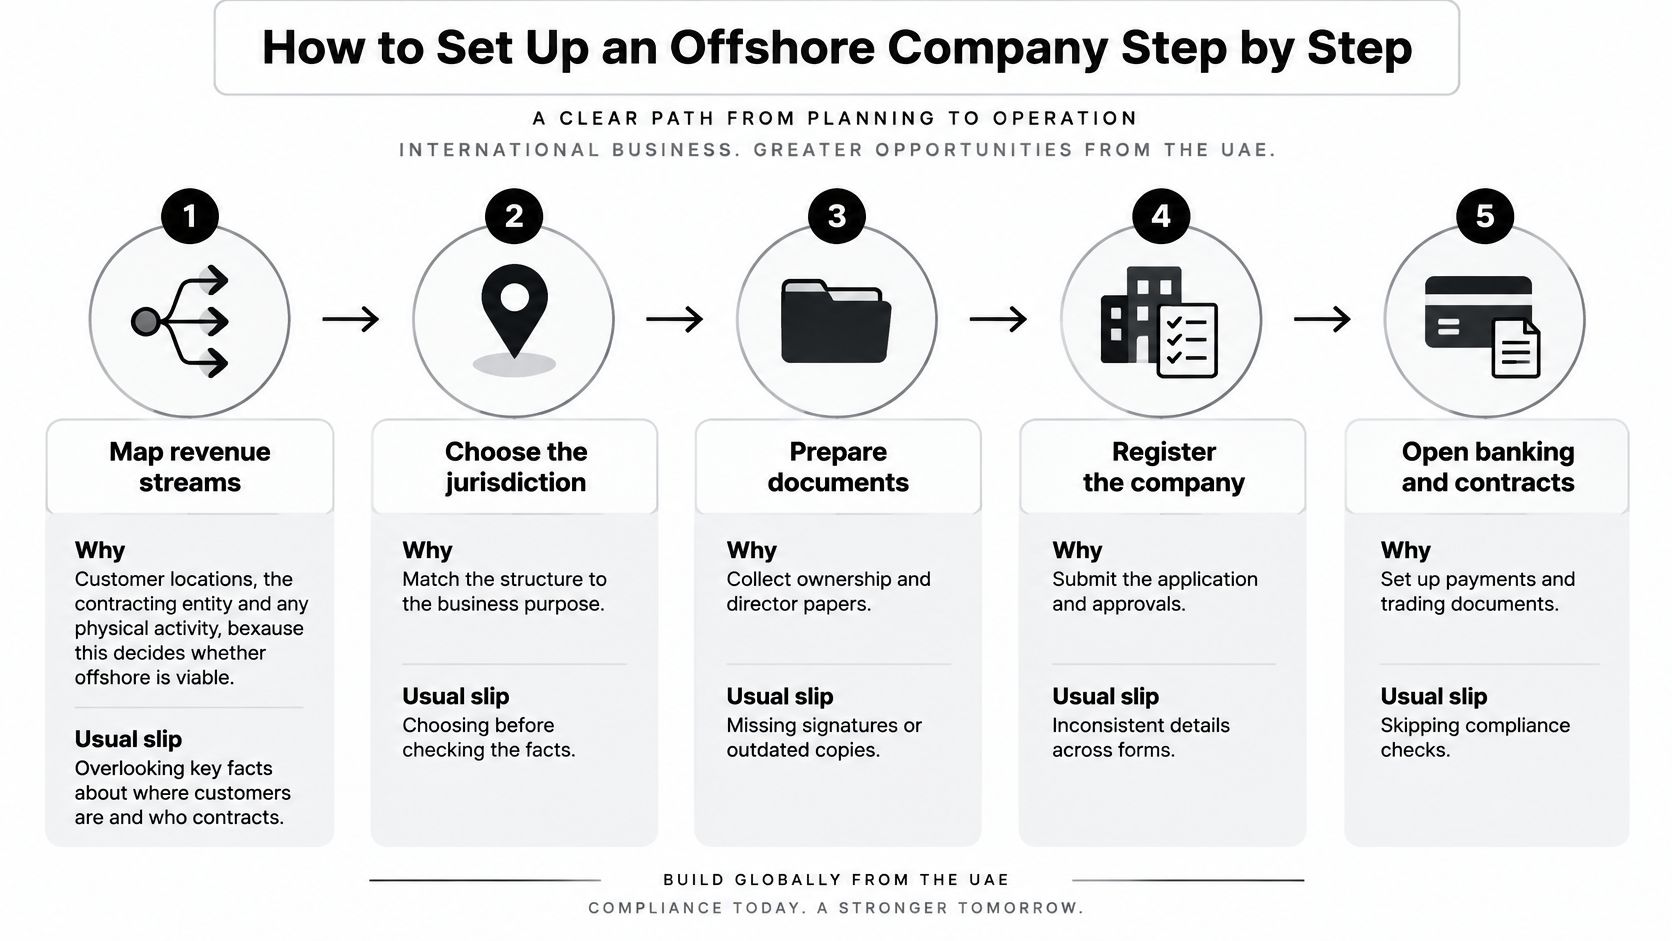
Treat formation as a sequence of decisions and evidence, not just an application form. The objective is a company whose documents, permissions, accounts and banking explanation describe the same business.
Complete the formation decisions in order
Map the proposed business. Record revenue streams, customer locations, the contracting entity and physical activity, because these determine whether offshore registration is viable. The common slip is selecting a package before establishing what the company must do.
Choose the jurisdiction and structure. Match the written activity description to permitted purposes and available licensing routes. Don't choose solely by the registration fee or assume another entrepreneur's arrangement will suit your business.
Prepare corporate and ownership documents. Assemble identity, address, shareholder, director and ultimate-beneficial-owner information using the authority's document checklist. Inconsistent names, incomplete ownership chains and outdated copies create avoidable clarification requests.
Submit the application and agreed fees. Check that forms, supporting documents and the written quote describe the same entity and activities. A frequent mistake is treating an initial headline price as the complete scope of work.
Review the incorporation documents. Check names, ownership details and the activities authorised by the registration or accompanying licence. Don't start operating merely because a certificate has arrived.
Prepare the banking application. Build a file covering source of funds, business purpose, ownership, contracts and expected transactions. Our business banking account guidance helps frame that preparation, but account opening remains subject to the bank's checks and approval.
Establish the compliance calendar. Assign responsibility for accounting, corporate-tax registration and filing assessment, VAT review, renewals and ownership updates. The common slip is leaving these tasks unassigned until a deadline or information request arrives.
Finish with a bank-ready company file
A bank-ready file should let a reviewer follow the business without guessing. Include the incorporation documents, ownership chart, identification records, funding explanation, relevant agreements and a clear description of expected payments.
Make the narrative specific: who pays the company, for what, from where, and why the company sends money onward. If contracts aren't yet signed, distinguish proposed arrangements from completed business rather than presenting forecasts as established activity.
We offer company formation, offshore registration, PRO services, tax residency certificates, VAT-compliant accounting, audit and liquidation services. Coordinating formation with those ongoing requirements helps keep the legal entity and its administrative records aligned.
Smart Classic Business Hub offers offshore registration and company formation alongside PRO, accounting, audit and tax-residency-certificate services. Visit Smart Classic Business Hub to discuss your proposed assets, customers and operating activities, and request a structure review and written fee quote before registering.