You've received a letter from a foreign tax authority asking you to prove where you're tax resident, and the deadline is approaching. You hold a UAE residence visa, an Emirates ID, and a home in Dubai, so it may seem that the answer is obvious. In practice, those documents alone don't guarantee that the Federal Tax Authority will issue the certificate you need.
A tax residency certificate for an individual is evidence designed for a specific purpose and a specific period. The most important decision often comes before you upload a single document: choosing the correct 12-month window, particularly if you moved to the UAE, changed visa status, or divided your time between countries.
What Is a UAE Tax Residency Certificate and Why You Need One
A UAE Tax Residency Certificate, or TRC, is an official certificate issued by the Federal Tax Authority to confirm an individual's UAE tax residency for an eligible period. People commonly use it when a foreign tax authority, bank, employer, or business partner asks for formal evidence that the individual is resident in the UAE.
The practical problem usually starts with a foreign review. A tax authority may question whether income, investment returns, pension payments, or other cross-border amounts should be taxed in another country. Without suitable proof of UAE tax residency, you may struggle to request relief under an applicable double taxation agreement, or you may face a risk of being taxed twice while the authorities assess your position.
A visa is not the certificate
A residence visa and Emirates ID help demonstrate your connection with the UAE, but neither document automatically proves tax residency. The FTA assesses the facts supporting the application, including your presence in the UAE and, where relevant, your UAE residence, employment, or business activity.
That distinction matters for people who have recently arrived, travel frequently, or retain substantial connections overseas. A person can hold a valid UAE residence permit and still have difficulty supporting an application if the selected period, entry and exit record, or evidence of UAE activity doesn't match the claim.
Treaty and domestic purposes
The FTA allows a natural person to apply through EmaraTax for a certificate for treaty-related purposes or for domestic and other purposes, as explained in the FTA guide to tax residency and Tax Residency Certificates. The purpose you select should match the request you're answering.
A treaty-purpose application is generally connected with relief under a double taxation agreement. A domestic-purpose application may be relevant when an organisation needs formal UAE tax residency evidence for an administrative or compliance reason. The certificate isn't a generic annual document that remains useful for every future situation. It relates to an eligible current or past 12-month period, and the period must be chosen carefully.
Practical rule: Treat the TRC as targeted evidence. Match the purpose and 12-month window to the exact question being asked by the foreign authority or institution.
If you need broader guidance on how personal tax matters fit into your UAE arrangements, review the personal tax guidance for UAE residents before submitting an application.
Understanding the Two Domestic Tax Residency Tests
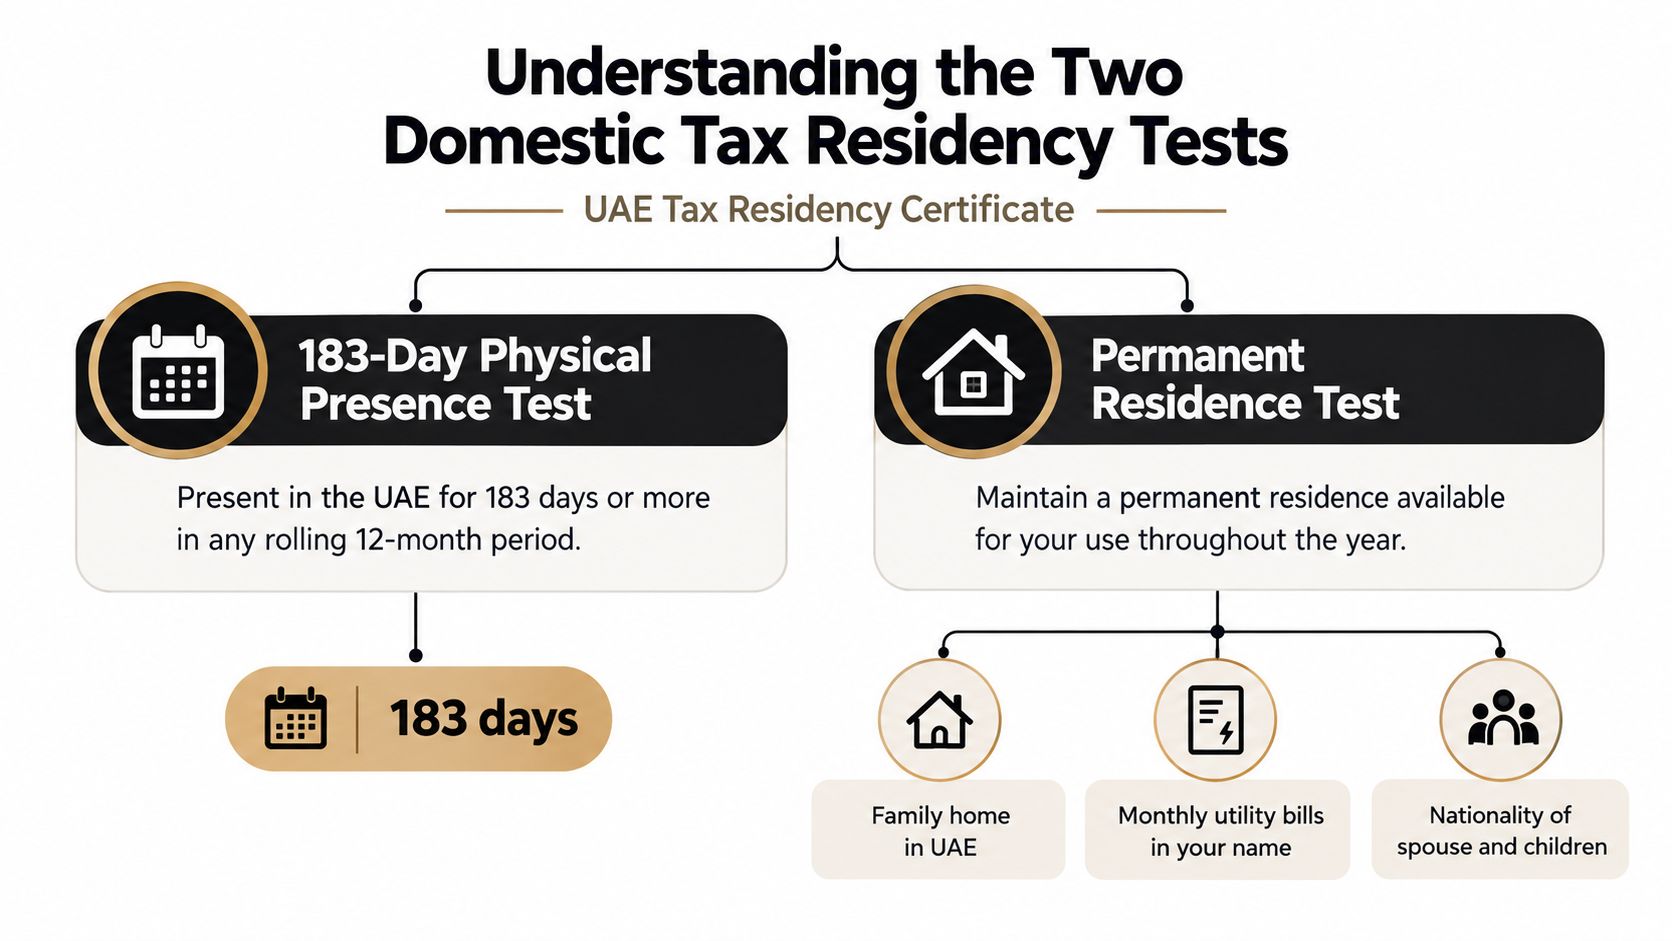
For domestic UAE tax residency, an individual generally starts by assessing the two main tests set out in the FTA's guidance. The first is based on physical presence. The second combines physical presence with status and a genuine UAE connection.
The 183-day physical presence test
You may qualify where you've been physically present in the UAE for 183 days or more in a 12-month period. The period isn't necessarily the calendar year. That makes a rolling travel review essential, especially for consultants, investors, and executives who enter and leave the UAE regularly.
For example, a salaried employee living and working in Dubai for most of the year will usually have a straightforward day-count analysis. The key evidence is the official UAE entry and exit report, not an informal estimate based on flight bookings or memory.
Count the period that supports the certificate you need. If the foreign authority is reviewing a particular period, an unrelated 12-month window may not answer its request even if you meet the physical presence requirement elsewhere.
The 90 to 182-day route
The second route can apply where the individual has been present in the UAE for 90 to 182 days in a 12-month period, but additional conditions must also be met. The person must be a UAE or GCC national, or hold a UAE residence permit, and must have a permanent place of residence or employment or business in the UAE.
A frequent traveller who divides time between London and Dubai may need to rely on this route. A UAE residence permit alone isn't enough. The applicant should be able to show the relevant home, employment, or business connection during the selected period.
That distinction is also important for people dealing with tax obligations in the United States. The right tax form choice for US expats depends on the person's wider facts, so a UAE TRC shouldn't be treated as a substitute for analysing obligations in the other country.
Evidence that supports the analysis
The FTA identifies supporting documents such as an Emirates ID or passport, an official UAE entry and exit report, and proof of UAE income or salary where applicable in its individual TRC service guidance. For the second route, the application should also be supported by evidence that reflects the UAE connection claimed.
A document checklist should therefore answer three questions:
- Who are you? Your identity and UAE status must be clear.
- Where were you? The entry and exit record must support the selected 12-month period.
- Why were you connected to the UAE? Employment, salary, residence, or business evidence should align with the route selected.
Choosing the Right 12-Month Period for Your Application
The period selection is where many otherwise well-prepared applications go wrong. The FTA allows an individual to request a certificate for the current, previous, or another past 12-month period, but not for a future period, as stated in its Tax Resident and TRC guide.
Start with the receiving authority's request. If a foreign tax office is examining a defined period, select a permissible 12-month window that encompasses the relevant facts and supports the purpose of the certificate. Don't select a convenient period merely because it includes your strongest UAE presence.
If you moved to the UAE mid-year
Suppose you relocated to Dubai during the year and the foreign authority is reviewing your position after the move. The useful window should reflect when you established your UAE connection and should be supported by your entry record, residence status, and UAE evidence.
A certificate for a period that starts before your move may not help if your UAE presence and supporting documents only begin later. Conversely, choosing a period that ends before you arrived cannot prove UAE residence during the period under review.
If your visa status changed
A move from a visit visa to a UAE residence permit creates a documentation issue, not an automatic answer. Build the period around the facts that support the selected domestic test. If you rely on the route requiring a residence permit, check that the permit existed during the relevant period and that your residence, employment, or business evidence is consistent with it.
The certificate should tell one coherent story. Identity documents, immigration records, employment evidence, and dates shouldn't contradict one another.
If the foreign authority specifies a period
When a foreign tax authority names a review period, prioritise that request over a more convenient application window. A certificate covering a different period may be formally valid but practically unhelpful.
The right question isn't “Which period is easiest?” It's “Which eligible period proves the facts the recipient is testing?”
Before submitting, write down the requested period, the selected 12-month window, the purpose, and the evidence supporting each month or travel pattern. If those four points don't align, pause before filing.
Required Documents and the EmaraTax Application Process
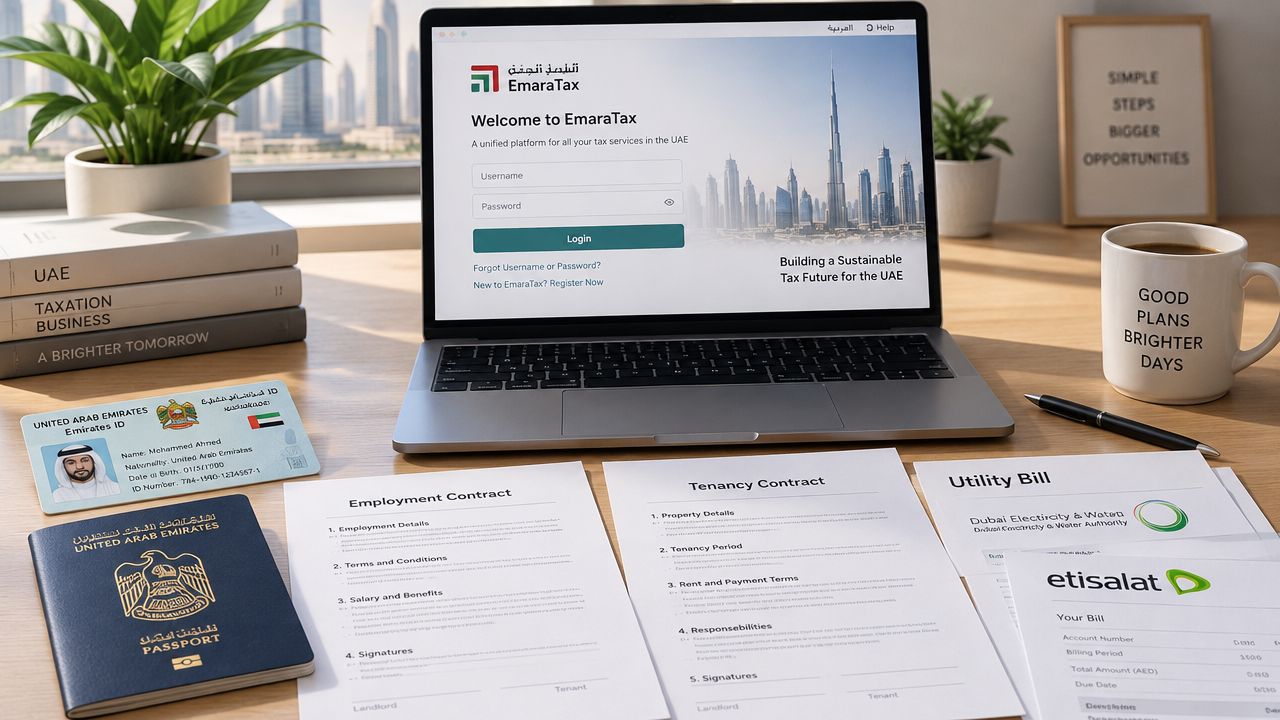
A strong application begins with consistent documents. The FTA's service guidance identifies core evidence such as an Emirates ID or passport, an official entry and exit report, and proof of UAE income or salary where applicable. The documents should support the particular period and purpose selected, rather than just demonstrate that you've had a UAE connection at some point.
Prepare the file before opening the portal
Organise the application around these evidence groups:
- Identity and status: Keep a clear passport copy and Emirates ID available, with names and identification details matching the application.
- Immigration history: Obtain the official UAE entry and exit report for the selected 12-month period.
- UAE income evidence: Where applicable, include proof of salary or UAE income that supports your employment or economic connection.
- Residence or activity evidence: If you rely on the route for people present between 90 and 182 days, prepare documents showing your permanent place of residence or UAE employment or business.
Some applicants also prepare supporting items such as a tenancy document, employment contract, salary certificate, or bank evidence. These may help explain the facts, but they should be relevant and consistent rather than uploaded in bulk without context.
Submit through EmaraTax
The workflow is straightforward, but the choices within it require care:
- Log in to the FTA's EmaraTax portal.
- Select the individual Tax Residency Certificate service.
- Choose treaty-related or domestic and other purposes.
- Enter the eligible current or past 12-month period.
- Upload legible documents that support the selected test.
- Review names, dates, status details, and the stated purpose.
- Submit the application and monitor communications from the FTA.
Before filing, compare the date on each document with the period entered in EmaraTax. A clear scan won't fix a date mismatch.
The FTA may request additional information, and an application can be approved or rejected. A UAE visa or Emirates ID doesn't make approval automatic. Respond to any query directly, identify the document answering each point, and avoid sending unrelated material that makes the file harder to assess.
For connected compliance work, you can also review VAT filing support for UAE businesses, particularly if your TRC application sits alongside business tax administration.
Real-World Case Studies for Different Applicant Profiles
The following examples use the decision patterns practitioners see regularly. They're illustrative scenarios, not guarantees of approval. The FTA assesses the evidence submitted for the individual and the selected period.
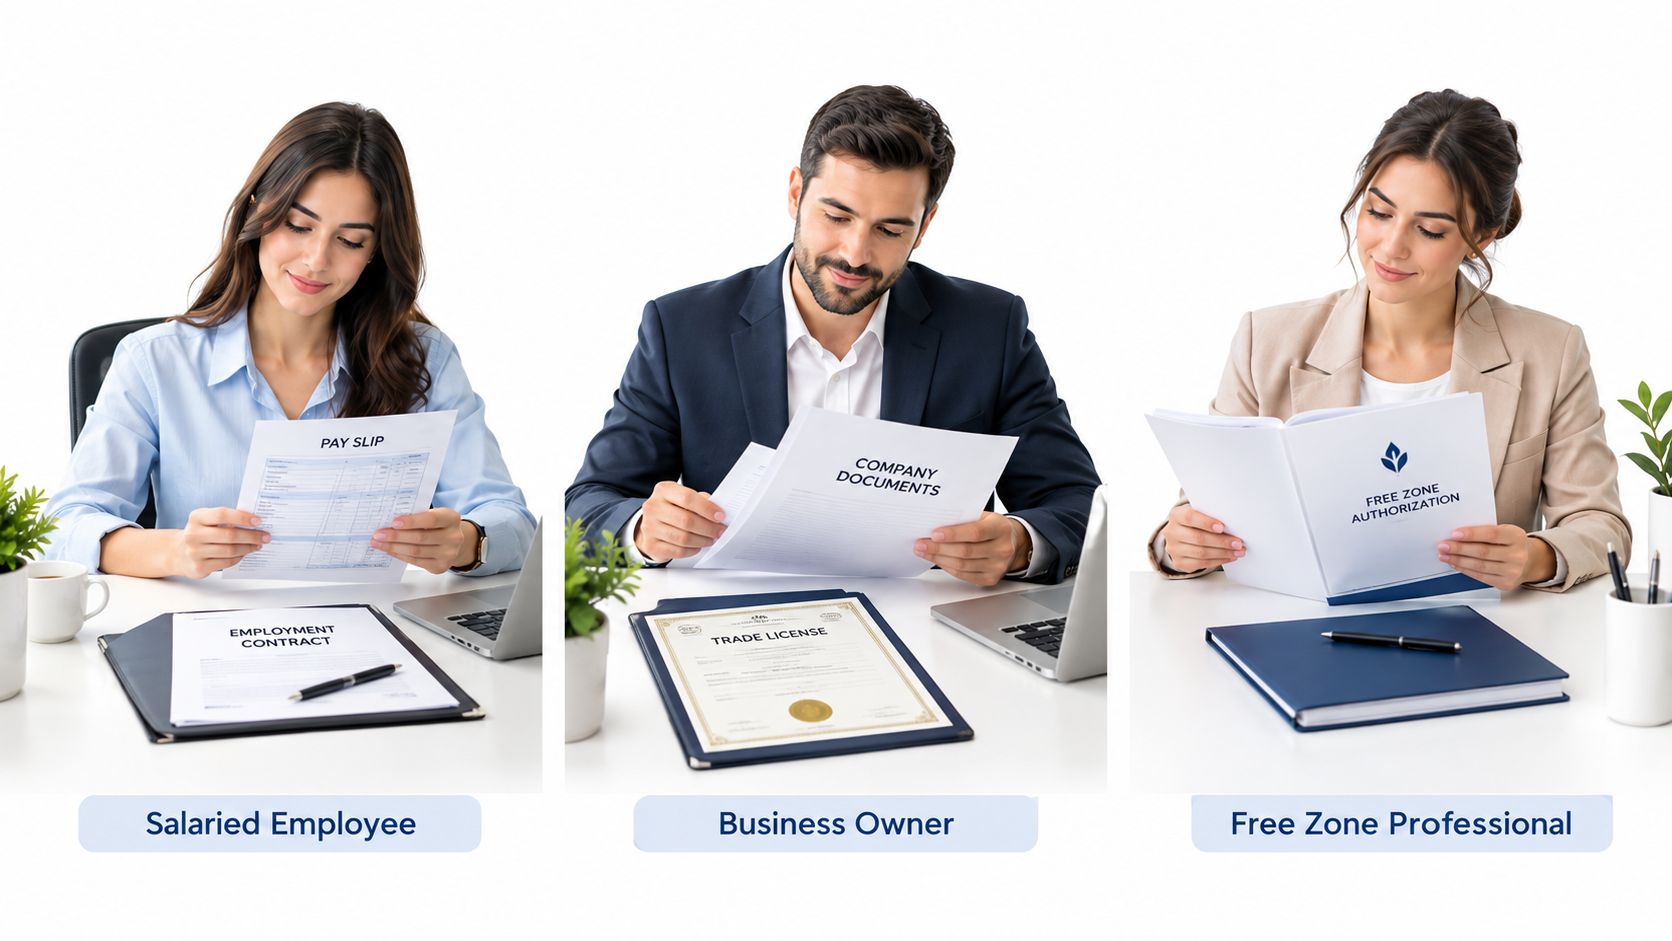
The Dubai employee with a clean travel record
A salaried employee lives in Dubai under a UAE employment arrangement and spends most of the relevant period in the country. The employee needs a treaty-related certificate for a foreign review.
The practical route is the physical presence test. The employee gathers a passport copy, Emirates ID, official entry and exit report, and proof of salary or UAE employment. The selected window is the one requested by the foreign authority, provided it's a current or past 12-month period permitted by the FTA.
This is the simplest profile because the day count and employment evidence point in the same direction. The application still needs a careful date review. A travel record covering the wrong window can undermine an otherwise clear case.
The investor with regular international travel
A free-zone business owner spends substantial time outside the UAE but holds a UAE residence permit and maintains a genuine UAE business connection. The person's presence falls within the 90 to 182-day range for the selected period.
Here, the second domestic route may be relevant. The applicant assembles the official entry and exit report, passport and Emirates ID evidence, residence permit information, and documents showing the UAE business or permanent residence connection.
The trade-off is clear. This route can fit a mobile investor's facts, but it's more document-sensitive than a straightforward high-presence application. A licence by itself may not explain the individual's actual UAE activity, so the evidence should match the claim being made.
The mid-year relocation
A professional leaves another country and relocates to Dubai during the year. The foreign tax authority asks for proof connected with the period after the move, while the applicant's UAE residence permit begins after arrival.
The application should focus on an eligible 12-month window that captures the relevant UAE residence facts and supports the authority's review. The applicant gathers the entry and exit report, identity documents, residence status evidence, and proof of UAE employment or income where applicable.
The main risk is choosing a window that looks convenient but doesn't match the relocation timeline. If the certificate overlaps a period in which the applicant was still demonstrably connected to the former country, the receiving authority may ask further questions. Period selection and cross-border advice should therefore be handled together.
Processing Times, Rejection Risks, and Common Pitfalls
The FTA guidance confirms that an application may be approved or rejected and that further information may be requested. That means applicants should assess the quality of the file, not assume that portal submission equals issuance.
| Factor | Detail |
|---|---|
| Processing | Timing depends on the completeness of the application and whether the FTA requests further information. |
| Review questions | The FTA may ask for documents or explanations that clarify identity, presence, purpose, or UAE connection. |
| Rejection risk | Applications can be rejected where the submitted facts or evidence don't support the request. |
| Period selection | The requested window must be a current or past eligible 12-month period, not a future period. |
| Visa assumption | A residence visa or Emirates ID doesn't, by itself, establish that the certificate should be issued. |
Where applicants create avoidable problems
Incomplete evidence is a common weakness. An application may include a passport and Emirates ID but omit the official immigration report or fail to provide proof relevant to the selected route.
Mismatched details cause another problem. Names may appear differently across documents, or the dates on an employment document may not fit the selected period. Those inconsistencies invite questions that a careful pre-submission review could prevent.
Period and purpose errors
Selecting treaty-related purposes when the recipient needs domestic evidence, or choosing domestic purposes when a foreign tax authority is asking for treaty support, can make the certificate unsuitable. The correct answer depends on the request you're responding to.
A future period is also unavailable. If you haven't yet completed the relevant facts, you can't solve the problem by requesting a certificate for an anticipated period.
A practical pre-submission review
Use a short review before pressing submit:
- Confirm the recipient's request: Identify the exact purpose and period stated by the foreign authority.
- Reconcile travel dates: Compare the selected window with the official entry and exit report.
- Match personal details: Check spelling, passport data, Emirates ID information, and dates.
- Test the evidence: Ask whether each uploaded document supports the route selected.
- Prepare for questions: Keep relevant supplementary documents ready in case the FTA requests clarification.
If the application involves a mid-year move, substantial time abroad, or a disputed foreign tax position, professional review can be more efficient than correcting a rejected or unsuitable application later.
When to Apply Professionally and How to Use Your TRC
Self-filing can work well when the facts are simple, the selected period is clear, and your documents consistently support the physical presence test. EmaraTax is accessible, and an applicant who understands the purpose, period, and evidence requirements may not need help with a routine submission.
Professional support becomes more valuable when the facts don't fit neatly. Mid-year movers, investors with several countries in the picture, applicants relying on the 90 to 182-day route, and anyone responding to an FTA query should consider having the file reviewed before submission.
Decide based on complexity
Use self-filing when:
- Your travel record clearly supports the selected period.
- Your UAE status and employment evidence are consistent.
- The receiving authority has made its purpose clear.
- No foreign residency conflict needs analysis.
Seek advice when:
- Your visa status changed during the relevant period.
- You're selecting between overlapping 12-month windows.
- You spend substantial time in another country.
- The FTA has requested additional information.
- A foreign authority is assessing double taxation or treaty relief.
A TRC should be given to the authority or institution that requested it, together with a clear explanation of the period and purpose when appropriate. Keep the application file, the submitted evidence, and the receiving authority's correspondence together. The certificate is period-specific evidence, not a permanent substitute for maintaining facts that support UAE tax residency.
If you also need to understand related identification requirements, consult this guide on how to get a tax identification number online and confirm what the relevant foreign authority requires.
Smart Classic Business Hub helps individuals prepare UAE TRC applications, organise supporting documents, and respond to period or evidence issues through its Dubai-based consultancy services. If your case involves a mid-year move, frequent travel, or a foreign tax review, visit Smart Classic Business Hub to discuss the application before you submit it.
Smart Classic Business Hub can review your eligibility, select a suitable 12-month period, and prepare the EmaraTax file for a UAE individual Tax Residency Certificate. Visit Smart Classic Business Hub to request practical support with your documents and application.