You've received a quote for an offshore company, and the registration package looks straightforward. But you're still unsure whether the company can hold your investments, receive client payments, or support the business you actually intend to run. Before paying, settle the more important question: does this structure fit your commercial purpose?
Setting up an offshore company in Dubai should start with the assets, activities and transactions you need to accommodate, not with the certificate you'll receive. My recommendation is simple: choose the legal environment first, build the evidence behind it, and treat incorporation as the beginning of your responsibilities.
Why Offshore Company Setup Requires Careful Planning
Consider a founder who wants a UAE company for international operations. Their initial description sounds clear, but it could mean holding shares in overseas subsidiaries, managing investments, or delivering consulting services from Dubai. Those are different business models, and they shouldn't receive an identical formation recommendation.
The practical starting point is a written statement: what will the entity own, manage, hold or transact, and where will those activities occur? Add who will make decisions and how money will move. An adviser can then assess the proposed structure against the intended use rather than reverse-engineering a justification for a package.
Separate the founder's objectives
A founder seeking an ownership vehicle should prioritise the assets it can hold, governance arrangements and future transfers. Someone planning an operating business should prioritise activity permissions and the proposed UAE footprint. Neither should assume that a convenient registration process resolves the other questions.
Dubai's international corporate environment provides useful context, not proof that every structure suits every investor. In its annual report for 2024, DIFC reported more than 6,920 active companies, a 32% year-on-year increase, alongside 1,823 new business registrations, up 39%. Those figures describe DIFC, not offshore incorporations, and shouldn't be used to imply otherwise.
Practical rule: Ask an adviser to explain why the proposed structure fits your intended activity before asking how quickly it can be registered.
Make the commercial brief specific:
- Assets: Identify the shares, investments or other interests the company is intended to hold.
- Activity: Distinguish ownership from services, management and trading.
- Location: State where work, decision-making and customer relationships will occur.
- Future plans: Flag anticipated staff, premises, investors or changes in business model.
If these answers remain vague, pause. A clearly defined purpose is more valuable than an early application.
Compare the Main Dubai and UAE Structures
Offshore, free-zone and mainland structures aren't interchangeable labels. Nor should DIFC be treated as a synonym for offshore registration. Compare them by the commercial question each environment needs to answer, then ask for confirmation of the selected entity's actual permissions.
The table below is a decision aid, not a statement that every entity within a category has the same rights. Activity, legal form and applicable approvals still need individual review.
Choosing the Appropriate UAE Business Structure
| Structure | Primary use | Key distinction | Question to answer first |
|---|---|---|---|
| Offshore jurisdiction | Proposed international ownership, holding or permitted cross-border arrangements | Suitability depends on the registrar's rules and intended transactions | Can this entity undertake the precise activities and hold the intended assets? |
| Free-zone company | A business assessed against a selected zone's activity and operating framework | Formation, operating permissions and qualifying tax treatment are separate questions | Does the chosen zone support the business model and required footprint? |
| DIFC entity | Corporate, investment or financial structures assessed within the DIFC environment | Entity selection and any regulatory authorisation must be considered separately | Does the proposed activity require specialist regulatory review? |
| Mainland operating company | A proposed UAE-facing operating business | The licence and approvals must match the actual work | What activities, premises and operational permissions does the business need? |
Test the structure against a real transaction
Suppose an investor wants an entity to hold subsidiary shares. The adviser should investigate ownership eligibility, distributions, governance and eventual disposal. Don't add an operating licence merely because it sounds more substantial, but don't select an offshore vehicle without checking the intended holdings either.
A consultant planning to work from Dubai needs a different assessment. The relevant questions concern service delivery, where the work takes place, who signs client contracts and what operating permissions are needed. Calling clients international doesn't answer those questions.
A founder proposing a financial activity should seek specialist advice before choosing an entity. Registration and permission to conduct a regulated activity are separate matters, so the formation decision must follow the regulatory assessment rather than precede it.
Use a business-structure selection discussion to compare the actual alternatives, including JAFZA or RAK ICC where an offshore route is under consideration. Request a written explanation of why the recommended jurisdiction fits, what it doesn't accommodate, and which questions remain subject to confirmation.
- Choose for current use: Base the decision on the transactions you expect.
- Allow for credible expansion: Explain likely changes without buying unnecessary complexity.
- Reject blanket rankings: The cheapest or most familiar jurisdiction isn't automatically the appropriate one.
The strongest recommendation identifies limitations as clearly as benefits. If an adviser can describe only advantages, ask for a more complete assessment.
Prepare Ownership Documents and Activity Evidence
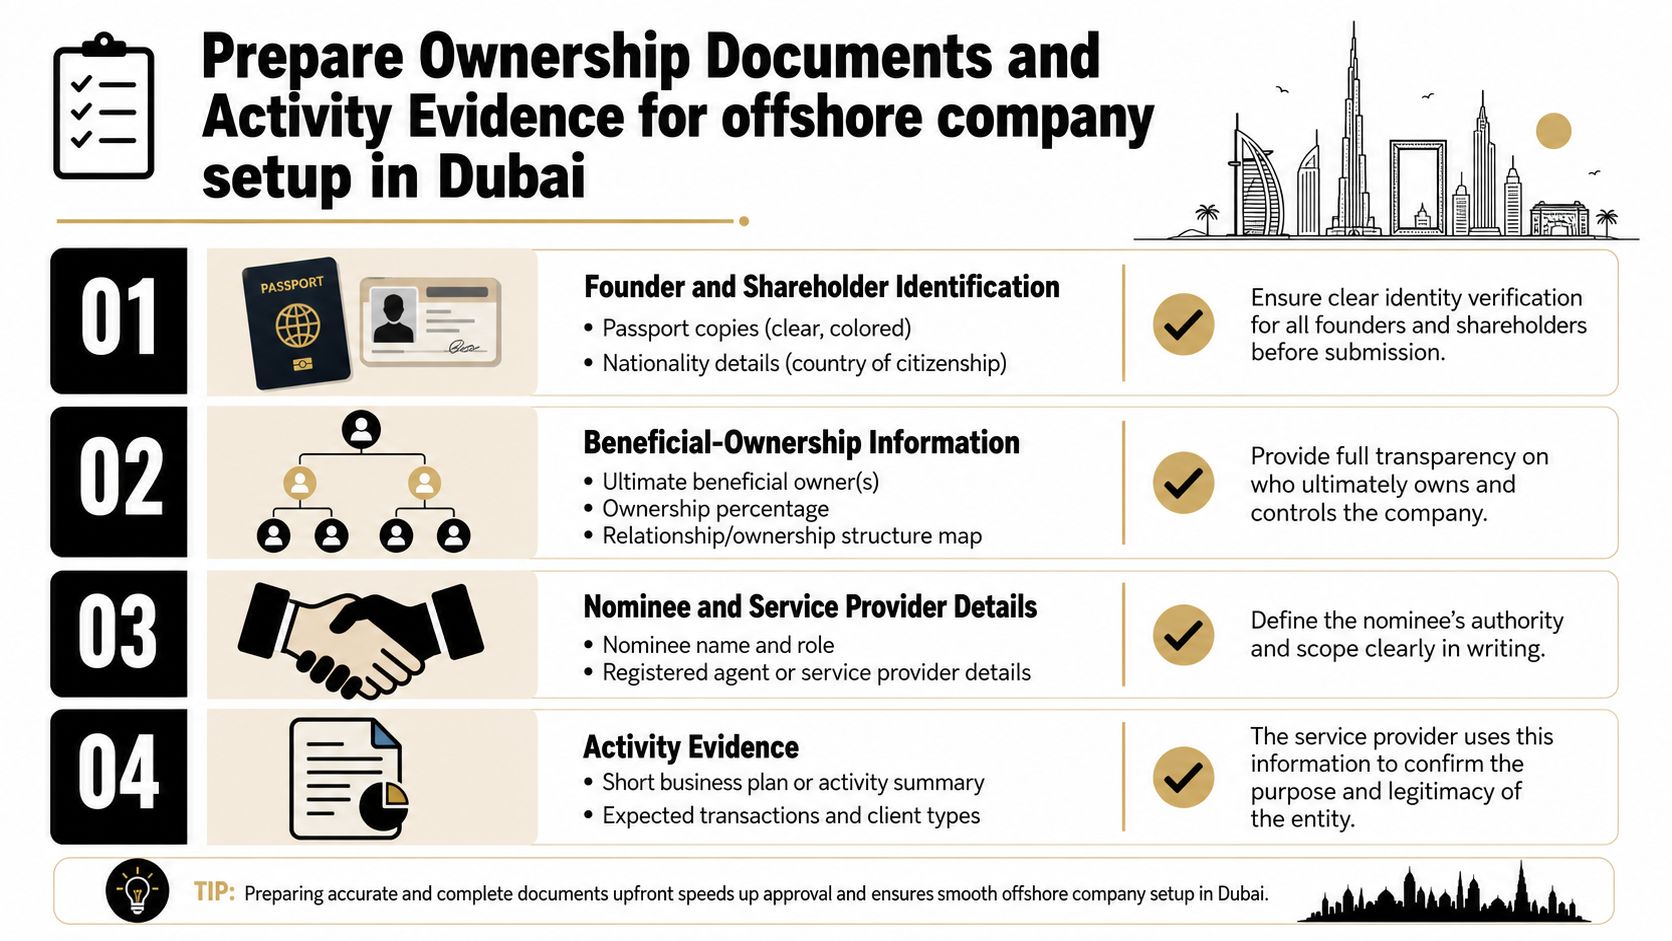
Build the application file around identity, control, authority and purpose. Don't send an unorganised collection of passports and expect the provider to infer the ownership structure. Give them a coherent explanation that they can check against the supporting documents.
Ask for a jurisdiction-specific document checklist before commissioning translations, certifications or legalisation. The provider should identify which documents are needed for your circumstances and explain any additional requirements arising from corporate shareholders or unusual arrangements.
Establish who owns and controls the company
- Founder and shareholder identification: Prepare clear passport details, identification information and address evidence for the relevant people, subject to the provider's confirmed requirements.
- Beneficial ownership: Draw the ownership chain through any intermediate entities to the individuals who ultimately own or control the proposed company.
- Directors and authorised persons: Explain who will approve decisions, sign documents and instruct service providers.
- Nominee arrangements: Define the proposed role, limits of authority, reporting expectations and termination arrangements in writing.
Nominal ownership, beneficial ownership and management responsibility shouldn't be treated as interchangeable. A name appearing in a corporate record doesn't, by itself, explain who makes decisions or benefits economically. Your documentation should make those relationships understandable.
Match the evidence to the proposed activity
For a proposed passive holding company, prepare an asset or shareholding schedule, the commercial reason for the structure, and an explanation of how acquisitions will be funded. Include available supporting records rather than describing the company merely as an investment vehicle.
A proposed management or operating company needs a different narrative. Explain the services, intended customers, delivery arrangements, decision-makers and expected transaction types. Draft agreements or genuine correspondence can help demonstrate the planned activity, but label drafts clearly and don't manufacture commercial history.
Nominee services should support documented governance, not conceal the person who ultimately controls the company.
Before submission, check that names, addresses and ownership descriptions agree across the application, supporting documents and structure chart. Ask the provider to resolve inconsistencies rather than submitting competing versions. This preparation also gives you a reliable reference when later advisers ask how the company was intended to operate.
Complete Incorporation and Activate the Entity
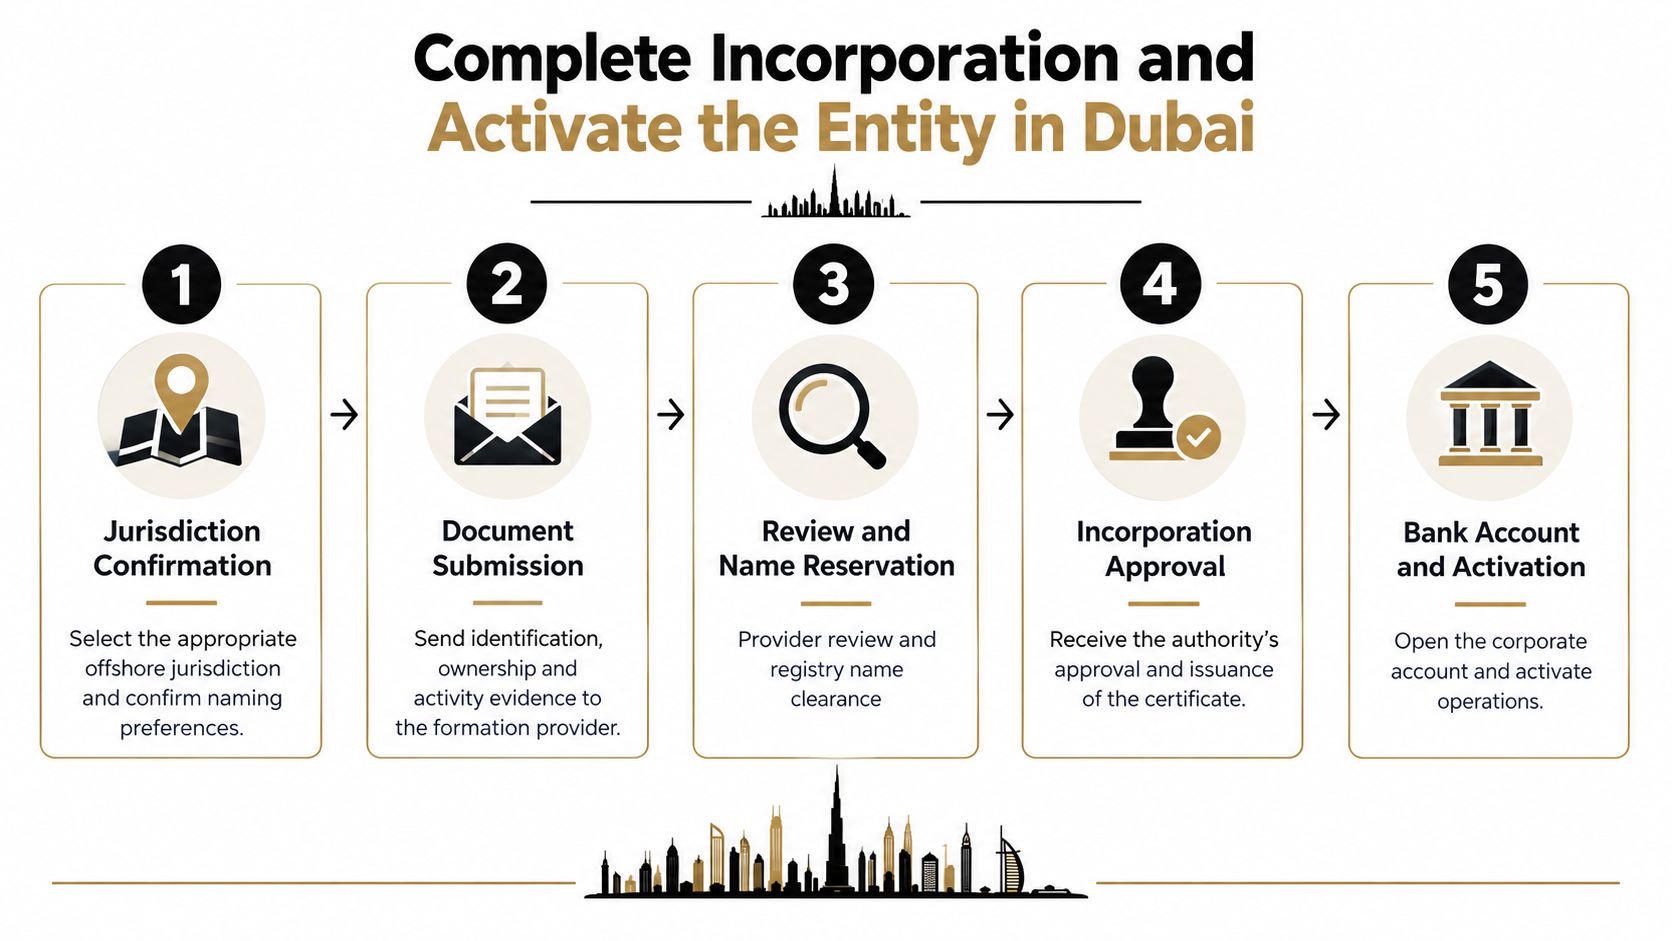
Once the structure and evidence are settled, manage incorporation as a controlled submission process. Approve what will be filed, retain what was filed, and reconcile what comes back. Delegating the application doesn't remove your responsibility to understand the final corporate arrangement.
Confirm the instruction before submission
Request a written scope identifying the jurisdiction, proposed activity, ownership, directors and services included. It should distinguish authority charges from professional services and identify any later work, such as banking preparation, accounting or tax review, that requires a separate instruction.
Before releasing final fees or sensitive documents, confirm:
- Service responsibility: Who prepares the application, submits it and answers authority queries?
- Address and administration: What registered-office or correspondence arrangements are included, and who monitors communications?
- Document handling: Which submission channel will be used, and how will sensitive information be protected?
- Ongoing costs: Which renewal, administration or other charges may arise, subject to the selected structure?
Smart Classic Business Hub is one option for entrepreneurs seeking formation, accounting, audit, PRO and compliance support through a coordinated service relationship. Whether you use a combined provider or separate specialists, ask who owns each task and how information will pass between them.
Control the application and collect the records
Have the provider review naming preferences and prepare the application against the confirmed requirements. Read the ownership, director and activity details before approving submission. If clarification is requested, keep the question, supporting response and revised document together.
Maintain a dated submission folder containing the approved application, signed documents, correspondence and final versions. Don't overwrite earlier files without preserving a record of what changed. That audit trail can help explain discrepancies later.
After approval, request the complete corporate package applicable to the entity, not just a certificate image. Check the registration evidence, constitutional documents, ownership records, director details and any associated resolutions or appointments supplied.
Activation is a separate readiness decision. Establish who can sign contracts, who maintains records and who authorises transactions before the company starts using its name commercially. Where a nominee is involved, ensure the signed authority arrangements match the governance model you approved.
Finish with a handover meeting. Ask the provider to explain the documents, outstanding actions and recurring responsibilities in plain language. An incorporation package you don't understand isn't a satisfactory handover.
Prepare the Company for Banking and Real Use
A certificate isn't a bank-account approval. Don't commit to customer payment dates on the assumption that incorporation makes the company immediately bankable. Treat banking as a separate assessment of the proposed account holder, its controllers and its expected activity.
The UAE's economic-substance guidance and wider compliance context underline the importance of examining actual activity rather than relying on the offshore label. For banking preparation, assemble a clear account of ownership, business purpose, funding and anticipated transactions instead of expecting the registration documents to explain everything.
Build the account narrative around the business model
An international holding company should be ready to explain its investments, acquisition funding and expected receipts. A consultancy should prepare an account of its services, customers and delivery arrangements, alongside confirmation that its chosen structure supports the proposed work.
A company expecting only occasional cross-border payments still needs a convincing explanation. Describe why the company receives the money, which counterparties are involved, the relevant countries and what records will support each payment. Low activity isn't a substitute for clarity.
- Ownership file: Make the control chain understandable without requiring the reviewer to reconstruct it.
- Funding explanation: Separate shareholder funding, loans and commercial receipts in your supporting narrative.
- Transaction evidence: Organise available contracts, investment records and genuine counterparty correspondence.
- Operating records: Decide how invoices, approvals and accounting entries will be retained after activation.
A nominee appointment or virtual-office package shouldn't be sold as a guaranteed route through onboarding. Reject guaranteed-account promises, especially where the provider hasn't reviewed the business model or explained the bank's separate assessment.
Keep account confirmation separate from onboarding
After an account exists, a counterparty may request evidence that it belongs to the company. The autobankstatement resource on a verify account ownership letter provides context for that document type, but any confirmation you supply must be authentic and acceptable to its recipient.
For business banking account preparation, ask for help assembling a consistent application rather than a promise of approval. The founder should be able to explain the account's purpose without contradicting the formation file.
Before approaching a bank, rehearse the explanation: what does the company do, who controls it, and what evidence will accompany its money movements?
If the answers depend on vague phrases such as general business or international payments, improve the file before submitting it.
Manage Tax and Ongoing UAE Compliance
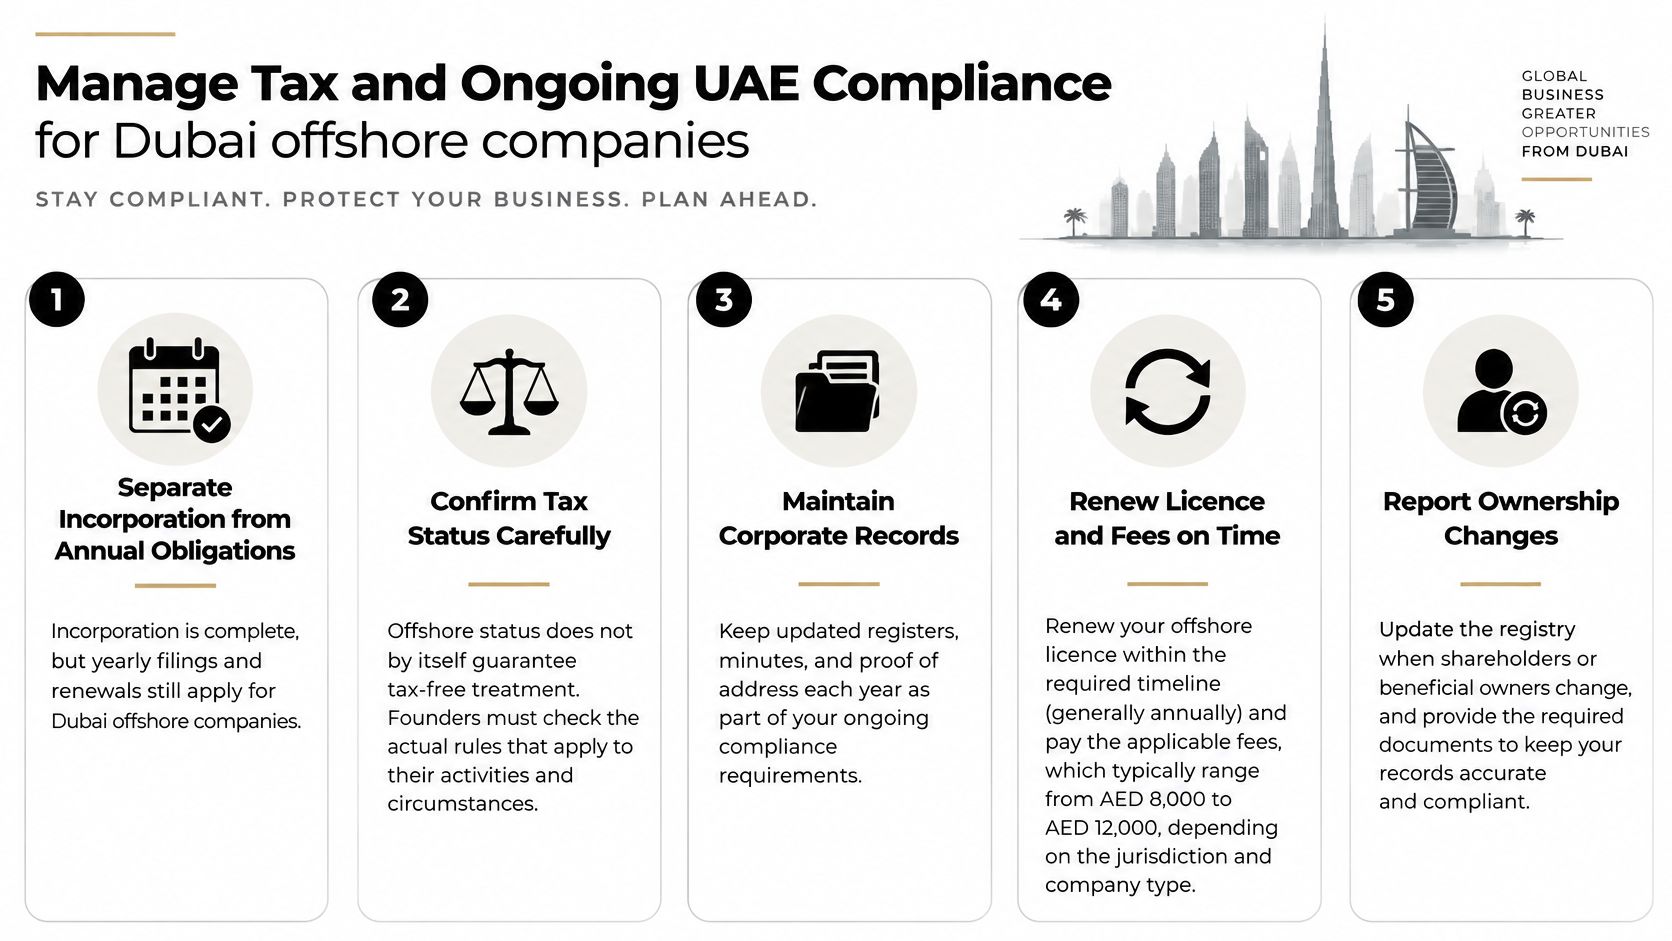
Treat tax status as a documented conclusion, not a feature included in an incorporation package. The analysis must address the entity's legal status, activities, income, substance, related-party dealings and applicable filing obligations. Don't apply free-zone assumptions automatically to an offshore company.
Under the Ministry of Finance's UAE corporate-tax framework, corporate tax applies to juridical persons established in a UAE free zone, while a qualifying free-zone person may receive a 0% rate on qualifying income when prescribed conditions are satisfied. That conditional treatment is not a blanket offshore exemption.
Make the accounting useful for tax decisions
Where the qualifying free-zone regime is relevant, the Ministry of Finance guidance on free-zone corporate-tax decisions sets out a non-qualifying revenue limit of the lower of 5% of total revenue or AED 5 million, with 9% corporate-tax treatment potentially relevant where income or the entity falls outside the preferential treatment.
Have the adviser confirm the consequences for your specific circumstances. Then organise the ledger so that income can be assessed by customer status, activity, source and related-party relationship. Don't leave classification until the filing deadline.
For administrative preparation, NAS Ledger's UAE tax registration help for SMEs can support a registration discussion; it shouldn't replace entity-specific advice. Obtain a written corporate-tax planning assessment that connects the legal structure to the accounting evidence.
Establish a compliance rhythm
Use an assigned calendar rather than a general promise that the provider handles compliance:
- Monthly: Update accounting records, retain supporting documents and classify receipts by their actual purpose.
- Quarterly: Reconcile the ledger with bank activity and contracts, review related-party transactions, and investigate unexplained differences.
- Annually: Confirm applicable filings, financial statements, registrar obligations, renewals and responsibility for submission.
- When circumstances change: Review ownership updates, director changes, new activities and altered payment flows before treating them as routine administration.
Economic-substance analysis also needs a period-specific answer. For holding, financing, intellectual-property or headquarters activity, ask which rules apply to the relevant period, whether any notification or reporting obligation remains, and what evidence must be preserved. Don't assume that older guidance establishes a current filing requirement.
Keep that review distinct from broader substance questions under tax rules. An absence of a particular economic-substance filing obligation doesn't answer every accounting, ownership or tax question. Assign each conclusion to a named adviser and retain the reasoning.
Verify Everything Before You Launch
Launch only when the company's purpose, permissions and supporting records agree. The final check isn't whether every document has a stamp. It's whether you can explain the structure to an adviser, bank or counterparty without changing the story.
Request a launch-ready handover
Ask for a final review covering the documents and unresolved decisions:
- Registration package: Obtain the complete applicable corporate records and confirm that the company details match the approved application.
- Ownership and authority: Verify the ownership chain, director appointments and written signing powers.
- Commercial readiness: Check that planned contracts and transactions fit the assessed activity.
- Banking preparation: Confirm who will manage enquiries and supply supporting evidence.
- Compliance ownership: Record who maintains accounts, monitors deadlines and submits each applicable filing.
- Open questions: List anything awaiting legal, tax or regulatory confirmation, with a named person responsible for resolving it.
Don't accept “we'll deal with that later” where the answer could change the structure itself. A minor administrative task can remain open; a material uncertainty about the intended activity shouldn't.
Proceed or pause on the evidence
Proceed where a proposed holding structure has a defined investment purpose, transparent control, documented authority and a reviewed compliance position. The company's records should support the transactions it is about to undertake.
Pause where the founder is relying on a tax-free assumption, an unexplained nominee arrangement or a certificate as a substitute for operating permission. Revisit the recommendation before signing contracts or moving funds.
The right offshore structure should be defensible in use, not merely easy to register. That's the standard to apply when setting up an offshore company in Dubai.
Smart Classic Business Hub offers offshore, free-zone and mainland company formation alongside accounting, audit, PRO and compliance support. Visit Smart Classic Business Hub with your proposed activity, ownership chart and expected transaction flows, and request a structure assessment that covers incorporation, banking preparation and ongoing responsibilities.