A name is reserved, a quote for offshore company registration is sitting in your inbox, and the bank's onboarding questionnaire is open in another tab. The quote lists a licence fee and a delivery date. The questionnaire wants the beneficial owner's passport, a proof of address, a business description and a signed ownership chart.
That gap is where most UAE offshore structures stall. Incorporation is rarely the difficult part. What derails applicants is a mismatch between what the licence permits, what the bank will accept and what the tax rules require for the income the company earns. One afternoon spent mapping those three things beats six weeks spent repairing them after the licence is issued.
Get the order right and registration is a paperwork exercise. Get it wrong and you own a licence you can't bank.
Which UAE Jurisdiction Fits Your Offshore Plan
The most expensive mistake in this process is choosing a registrar because the quote came in lowest. Three weeks later the founder discovers that the licence category doesn't name the activity the bank wants to see, and the file goes back to the start with a new fee attached.
The UAE's offshore environment grew out of its free-zone model rather than from a single nationwide offshore-registration statute. Jebel Ali Free Zone opened in 1985, and the country went on to develop more than 35 free-trade zones across logistics, trading, finance, media, technology and manufacturing, as UAE government guidance on the free-zone model records. That guidance states that free-zone companies may be 100% foreign-owned and that expatriate investors may repatriate all capital and profits.
It also says something founders skim past. Permitted activities, office requirements, access to the mainland market, reporting duties and visa eligibility all depend on the registering jurisdiction and the licence category. A UAE offshore entity isn't a lighter version of a mainland company. It's a different instrument with a narrower scope, and the scope is written into the licence.
Four registrars account for most of the market, and they don't compete on the same terms.
| Jurisdiction | Typically suits | Direct mainland trading | Main check before applying |
|---|---|---|---|
| RAK ICC (Ras Al Khaimah) | Holding companies, asset and IP ownership | No | Permitted activities list and bank acceptance |
| JAFZA (Jebel Ali Free Zone, Dubai) | Trading, logistics and regional distribution | Limited, needs a mainland licence | Licence scope and office requirement |
| ADGM (Abu Dhabi Global Market) | Financial services and common-law corporate structures | No | Whether regulated activities need separate approval |
| DMCC (Dubai Multi Commodities Centre) | Commodities and general trading | Limited | Office or flexi-desk rules for the chosen licence |
A holding company is not a trading company
A structure that owns shares or intellectual property behaves nothing like a company that invoices customers in Dubai, even when both are described as offshore. The holding company's real questions are about asset protection, dividend flow and where the board sits. The trading company's questions are about licences, customs, VAT and whether its customers can legally pay it at all. Same label, different instrument, different zone.
Four questions that settle the shortlist
- Will it hold assets? Shares, property or IP point you towards a holding-friendly registrar and a clean, provable ownership chain, because every later transfer has to be explained to a bank.
- Will it sign contracts with UAE customers? If yes, plan for a licensed mainland distributor, a branch or a separate mainland company rather than assuming the offshore vehicle can be the contracting party.
- Does it need a UAE bank account? Nearly every serious structure does, and the bank's view of your licence category matters more than the registrar's brochure.
- Does a director need a residence visa? Visa eligibility follows the licence and the zone, not the incorporation certificate on its own.
Practical rule: pick the zone whose licence category names your activity in its own words, then read the registrar's permitted-activities list before the company name goes on the application. If your activity isn't named, the licence will describe something adjacent, and the bank will ask about the difference.
Before you compare fees, write one paragraph: what the company will do, who pays it, and the three counterparties that will account for most of its revenue. That short list usually reduces four options to one or two, and it gives your adviser, your bank and your auditor the same story to work from.
Test the Tax Position Before You Incorporate
Offshore status doesn't answer the tax question. Income does. Before comparing registrars, put every expected revenue stream on its own row and answer six things for each: where the customer sits, where the work happens, who signs the contract, where the goods move, where management decisions are taken, and what records you can produce to prove all of it.
The baseline rate is settled. Corporate tax applies from the first financial year beginning on or after 1 June 2023, at 0% on taxable income up to AED 375,000 and 9% above that threshold, and the official UAE corporate tax guidance is explicit that juridical persons established in free zones fall within the scope and must register for tax. Free-zone status is a separate test, not an exemption from the framework.
Then test the rest stream by stream: VAT registration and filing where turnover brings you into scope, corporate tax registration and the annual return, transfer pricing for related-party contracts, economic substance for relevant activities, and any tax exposure in the customer's country. Treat them as five separate questions, because they have five separate answers.
The matrix, not the label
| Scenario | Question to answer | Evidence to keep |
|---|---|---|
| Passive holding company | Does the income come only from dividends or capital gains on holdings? | Share register, dividend records, board minutes |
| UAE property ownership | Does the rental income count as taxable business income in the UAE? | Title deeds, lease agreements, rental ledger |
| Consulting delivered from Dubai | Is effective management in the UAE, which may affect tax residence? | Contracts, travel records, meeting minutes showing where decisions are made |
| Transactions with UAE-connected parties | Do related-party contracts change the taxable income or require transfer-pricing records? | Invoices, contracts, transfer-pricing file |
Where the director sits changes the answer
Effective management is the quiet variable. A director who runs the company from a Dubai desk, signs from Dubai and holds board meetings in Dubai has moved the centre of decision-making into the UAE, and that can shift the tax residence analysis regardless of where the entity was incorporated. Keep the minutes, the travel pattern and the contracts consistent with the position you take with the bank and the tax authority, because the two will eventually compare notes.
Pick the two income streams most likely to materialise and complete the matrix for each before you commit to a jurisdiction. If an answer stays unclear, that's the moment to pay for advice, not the week after the first invoice goes out.
Who Appears on the Register
Nominee shareholders generate more confusion than any other structure question. Founders ask whether a nominee keeps their name off the file. That isn't how it works. A nominee changes what the register records as the shareholder; it doesn't remove the requirement to name the human being who owns or controls the company.
The register is a disclosure document, not a confidentiality product.

Three ownership setups appear on UAE files, and each carries a different disclosure burden.
| Structure | Who holds the shares on record | What must be disclosed | Main risk |
|---|---|---|---|
| Direct shareholder | The founder | Founder's identity and beneficial-owner details | Full personal exposure on the record |
| Nominee shareholder | Nominee, with the founder as beneficial owner | Nominee arrangement and beneficial-owner details | Undeclared or poorly documented nominee arrangement |
| Corporate shareholder | Another company in a layered chain | Each layer traced to natural persons | Tracing delays at onboarding and banking |
What the registrar asks for
- Passport copies for every shareholder and director, matching the name on the constitutional documents exactly.
- Proof of address for each of those individuals, recent enough for the bank to accept it later.
- Constitutional documents, prepared for the legal form rather than copied from another entity.
- A signed ownership declaration stating each owner's percentage and any nominee, trust or similar arrangement.
Control is the threshold that decides who gets named. The Central Bank of the UAE rulebook requires registrars to identify individuals owning or controlling at least 25% of a company, and UAE beneficial-owner guidance applies the same threshold by ownership or voting rights, covers control through other means, and designates a senior managing official where no individual meets the test, as this summary of UAE beneficial owner disclosure rules explains. Confidentiality in practice means restricted public visibility, not anonymity, and it never extends to the regulator.
Ownership evidence is also a tax document. The UAE has 193 double-taxation agreements, but access to any of them depends on the entity's facts, residence status, beneficial ownership and the substance requirements that apply, not on possession of a registration certificate, as the UAE corporate tax framework sets out.
Expect the file to travel. Personal information is shared with government authorities such as DED, immigration, notary and free zones as required for business setup and visa services, so an inconsistency between the passport, the declaration and the constitutional documents follows you into every later application.
Map each ownership layer to a named person with supporting evidence before you choose the structure. Doing it at the end is how files get rebuilt from scratch.
Registration Costs and Timeline
Cost estimates go wrong for a predictable reason. Founders budget for the licence and forget everything that surrounds it.
- The licence fee for your registrar and legal form. Ask for the figure attached to the category you'll hold, not the cheapest line on the schedule.
- Registration and name reservation fees, which registrars usually quote separately from the licence.
- Office or flexi-desk obligations. Some categories require a physical desk or a serviced office, and the requirement follows the category rather than your preference.
- Document legalisation, attestation and translation, including anything the registrar wants certified before review.
- Bank onboarding charges and the annual renewal, which recurs whether or not the company traded.
Timeline follows the same logic as the file. The activity check and the ownership file come first, because an incomplete ownership file is the most common reason an application sits in review. Licence issuance follows the registrar's own assessment. Banking can run in parallel, but a bank will only start once the ownership file and the business description are complete.
A fast licence with a slow bank account isn't a fast setup. Ask the bank how long onboarding takes before you pay the registrar.
Request the fee schedule in writing for your chosen zone and keep it beside the structure note, so renewal gets budgeted rather than discovered. Do the same with the bank. Their onboarding list is a checklist you can satisfy in advance, and the founders who treat it that way are the ones who invoice in the first month.
How to Register an Offshore Company, Step by Step
Registration runs in five phases, and each one has a failure mode you can see coming.
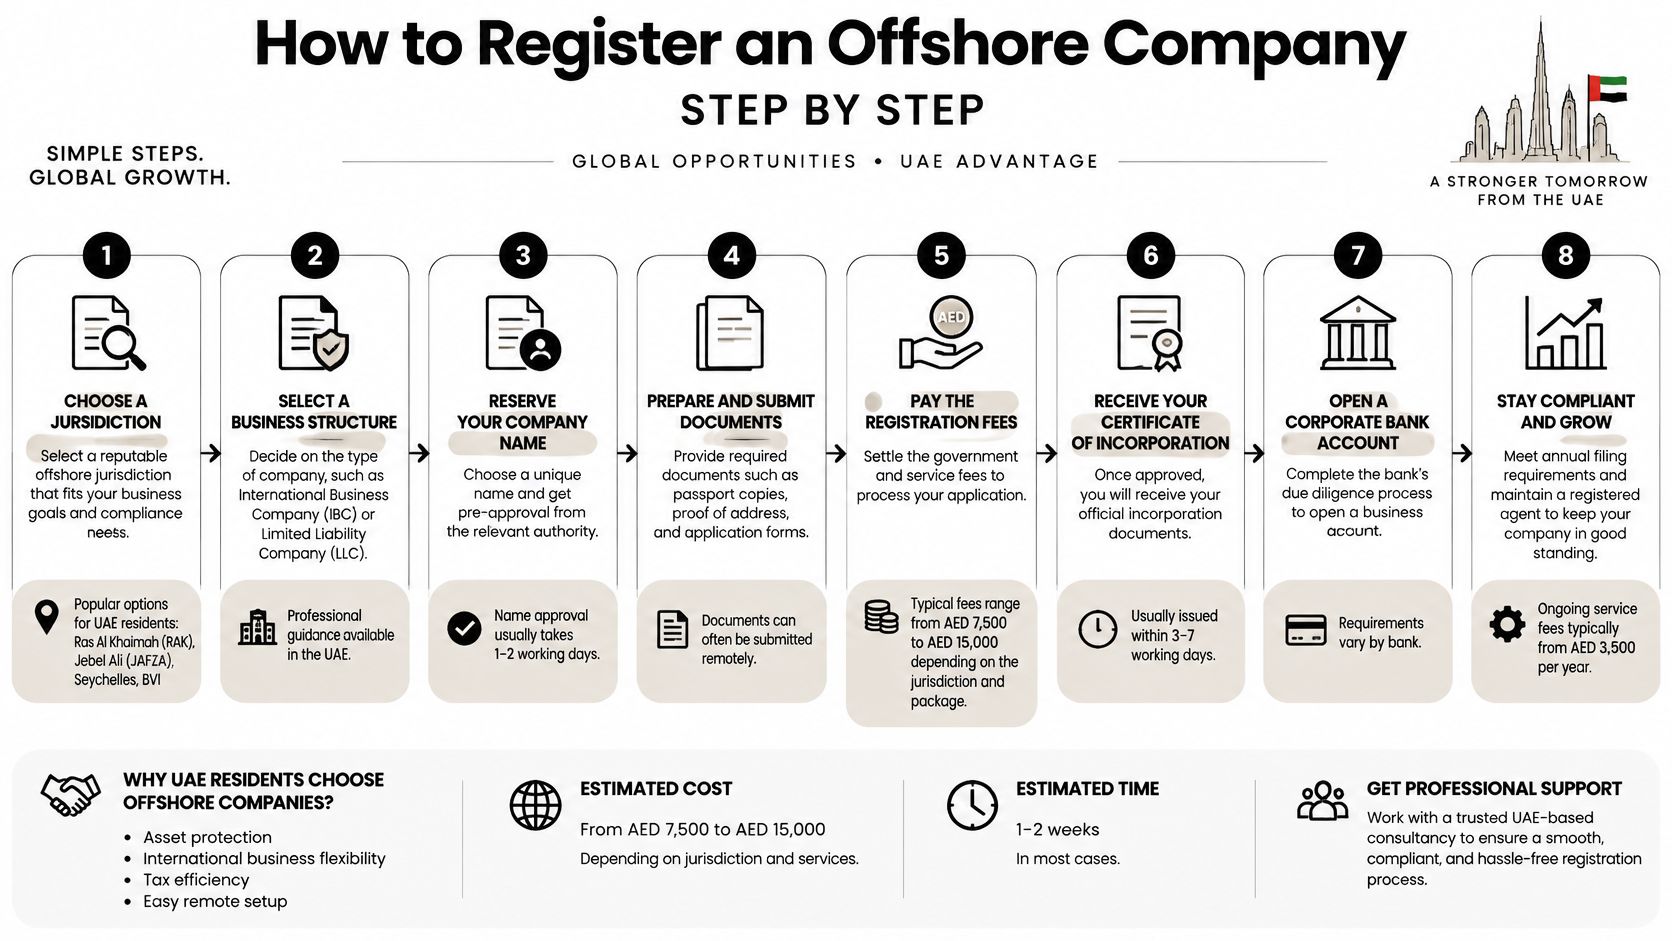
- Confirm the activity and the vehicle. A holding or IP company can sit offshore legitimately. A company selling to UAE mainland customers usually needs a mainland licence, a branch or a distributor. The costliest slip is an activity description that doesn't match the zone's permitted list, because the licence then describes something adjacent to what you do.
- Choose the registrar and the legal form. Confirm the form can hold the licence you need before you reserve a name. Picking a zone for its price rather than its permitted activities is the same mistake wearing a different hat.
- Build the ownership file. Constitutional documents, passport copies for every shareholder and director, proof of address, and a beneficial-owner declaration stating each owner's percentage and any nominee, trust or similar arrangement. The slip is a detail that doesn't match the passport, often a middle name or a spelled-out first name.
- Take the licence and keep the records. File the registrar's documents with dated submission receipts. Ownership changes must be reported to the Registrar within 14 days, so name one officer to monitor them and keep proof of each filing, as the UAE free-zone registration requirements set out. Fourteen days is short enough that an unmonitored change becomes a breach before anyone notices.
- Map banking, tax, substance and reporting before trading. Run the income matrix from the earlier section across the new entity. The slip is issuing an invoice before the bank account and tax registration are live, which turns a clean setup into a reconciliation exercise with your auditor.
Our own sequence starts one step earlier, with an initial consultation and assessment where we learn the business requirements and objectives and work out which PRO services the engagement needs, whether that's company registration, visa processing or a government approval. It's cheaper to answer those questions before a name is reserved.
Banking, Substance and Reporting
The licence is the start of the obligations, not the end of them. Registration alone doesn't establish tax exemption, secrecy or immunity from substance and reporting duties, and the framework behind those duties sits in the UAE Government's business laws and compliance guidance.
Open the corporate bank account early. Banks ask for the ownership file, a business plan and proof of the activity, and every extra round of questions pushes the first receipt further out. Submit a file that agrees with itself and onboarding moves; submit one that argues with itself and it doesn't.
The duties that start after the licence
- Economic substance. Mainland and free-zone entities conducting specified relevant activities must maintain adequate economic presence in the UAE, submit an annual notification and, where applicable, file an Economic Substance Report within 12 months after the financial year ends.
- Corporate tax. Entities in scope register and file, and the qualifying free-zone conditions get tested against actual income rather than assumed at incorporation.
- VAT. Registration and filing once turnover brings the company into scope, with records that reconcile to the bank statements.
- Licence renewal. Annual, and a lapse freezes bank access faster than most founders expect.
The compliance calendar
Diarise renewal dates, filing deadlines, bank review dates and the name of the officer responsible for each. We tell clients about the yearly compliances every UAE company must follow, because these deadlines are annual, they don't announce themselves, and the person who handled the setup has usually moved on by the second cycle.
One file, dated. Keep every submission receipt, licence copy and filing acknowledgement in a single compliance file. When a registrar or a bank asks, you answer in days instead of weeks.
Registration doesn't discharge any of this. It tells you which clock started.
Compliance Traps That Delay or Derail a Registration
Four beliefs cause most of the damage, and every one of them can be corrected before the file is submitted.
Work through the checklist below against your own structure. It takes about ten minutes and it surfaces most of what a registrar or a bank would otherwise surface for you.

- "Offshore means anonymous." It doesn't. A registrar who learns about a new shareholder months after the event treats it as a compliance failure rather than an administrative slip. Fix: a monthly ownership check against the register file, one named officer, dated proof of every submission.
- "We'll sort out the mainland question later." Selling to UAE customers from an offshore vehicle is the classic structural fault. By the time it's discovered, invoices have been issued and the repair is a distributor agreement or a second entity, not a licence amendment. Fix: document the sales route before the first invoice, whichever route you choose.
- "The bank will work around a small discrepancy." Rejections usually trace to a document set that disagrees with itself: a name spelled differently on the passport and the constitutional file, a business description that doesn't match the licence category, an address that changed and was never updated. Fix: a line-by-line reconciliation of passport, declaration, licence and business description before the file is sent.
- "Renewal will come round again next year." With three or four entities the dates blur, and a lapsed licence stops the bank account working. Fix: a shared calendar carrying the renewal date, the renewal owner and the payment date, all set at least a month ahead.
The pattern behind all four is the same. Each one is a small administrative detail that becomes a structural problem once money has moved. None of them requires legal advice to prevent. They require somebody to own the dates.
Confirm Your Structure Before You Apply
Write a one-page structure note before any application goes in. It should list the activity, the jurisdiction and licence category, the ownership chain with every beneficial owner named, the expected income streams and the tax answer for each.
Then check the note against three documents: the business description on the bank file, the registrar's permitted-activities list and the licence category you applied for. A mismatch between those three is the most common reason an application is rejected or stalls, and no provider can repair an ownership file that contradicts itself.
Confirm the cost and timeline figures against the registrar's fee schedule, because the schedule is the only version that binds. If nominees, layered companies or income from several countries are involved, get an independent review before you file rather than after.
The pieces around the note are routine. Company formation, PRO services, offshore registration, tax residency certificates, VAT compliant accounting, audit and liquidation all follow from it. The note itself is the part that has to be right first, and it's also the part that tells you when your preferred jurisdiction is the wrong one.
Set the first compliance date in the calendar before the licence is issued, not after.
Smart Classic Business Hub works with founders and investors on offshore company registration in the UAE, from the first consultation through the licence, the bank file and the compliance calendar that follows it. If you're weighing a holding structure against a trading entity, the team can map the jurisdiction, ownership chain and tax position with you before anything is filed. Visit Smart Classic Business Hub to start that conversation.