You're probably in one of two situations right now. Either your offshore company is ready and the bank account is the missing piece, or you haven't incorporated yet but you already know banking will decide whether the structure works in practice.
That instinct is correct. In the UAE, offshore bank account opening is rarely blocked by the company registration itself. The main friction starts when the bank asks a harder question than most setup guides prepare you for: why does this business need this account, and what proves the activity is real?
A lot of applicants still approach offshore banking with outdated assumptions. They expect speed, discretion, and a light-touch review if the documents look formally complete. That isn't how UAE banks assess offshore clients. They assess risk, trace ownership, test consistency, and look for a business profile that makes sense on paper and in person. If that foundation is weak, the file slows down or stops.
Choosing Your Path Jurisdiction Structure and Substance
A common failure pattern looks like this. The company is already incorporated, the founder is pleased with the setup cost and timeline, and only then does the banking review expose the weak point. The jurisdiction fits company formation, but it does not fit the banking story.

Start with the bankable structure
Banks assess the company, the owners, the expected transaction flow, and the reason this account sits in the UAE. Those points are reviewed together, not as separate boxes on a form.
If you are comparing RAK ICC and JAFZA, incorporation speed should not drive the decision by itself. A structure can be quick to register and still perform poorly at account opening if the shareholding chain is layered without a clear reason, the activity is drafted too broadly, or the business has no convincing link to the UAE banking relationship.
I often see founders focus on what is easy to set up rather than what is easy to defend. That is expensive. Changing a weak structure after rejection usually means new documents, new explanations, and a second compliance review under tighter scrutiny.
The same issue appears when owners try to use a personal account as a temporary workaround. That approach raises concern about source of funds, beneficial ownership, and mixing company receipts with personal money. For a commercial operation, banks expect a proper corporate account, defined signatories, and a clear separation between business and personal transactions.
Practical rule: choose the jurisdiction and ownership model only after checking whether the business activity, shareholder profile, and expected payment routes will make sense to a UAE bank.
Substance matters more than secrecy
This is the point generic offshore banking guides often miss. Offshore banking is not an anonymity exercise. UAE banks want to see who owns the company, what the business does, where the money comes from, and why the account belongs in that structure.
For non-resident directors in particular, the difficult question is usually substance. Banks want evidence that the company has a genuine operating purpose. Aston's guidance for non-resident directors notes that weak files often fail where they cannot show credible business activity and a logical commercial footprint.
That does not always require a large office or full local team. It does require a file that answers practical questions with specifics, not slogans:
- Revenue flow: who pays the company, in which currencies, and for what service or goods?
- Payment flow: which suppliers or counterparties are paid, from which countries, and why from this account?
- Commercial logic: why is an offshore vehicle appropriate for this activity instead of a mainland or free zone entity?
- UAE connection: what ties justify banking in the UAE if the owners live elsewhere?
- Operating proof: which contracts, invoices, counterparties, or business relationships support the application?
Many applicants encounter difficulties. “General trading” or “consultancy” can appear on a licence, but a bank still wants to know what is being traded or advised, who the counterparties are, and how the transaction pattern will look in practice.
Decide before incorporation, not after rejection
Strong applications are planned backwards from the compliance review. That means pressure-testing the activity wording, shareholder disclosures, signatory setup, and transaction profile before the company is formed.
A simple planning model helps:
| Decision area | Weak approach | Strong approach |
|---|---|---|
| Jurisdiction | Chosen for speed only | Chosen for fit with the banking profile |
| Ownership | Added later without planning | Declared clearly from the start |
| Activity | Broad, generic wording | Specific and commercially coherent |
| Banking rationale | “Need an offshore account” | Clear use case linked to actual trade |
At Smart Classic Business Hub, we advise clients to treat offshore company formation and bank account opening as one decision stream. That usually shortens the process because the structure is built around what the bank is likely to accept, not around what looks convenient on day one.
Get these points right early, and the file stands on its own logic. Get them wrong, and every later document has to compensate for a structure that never matched the banking objective.
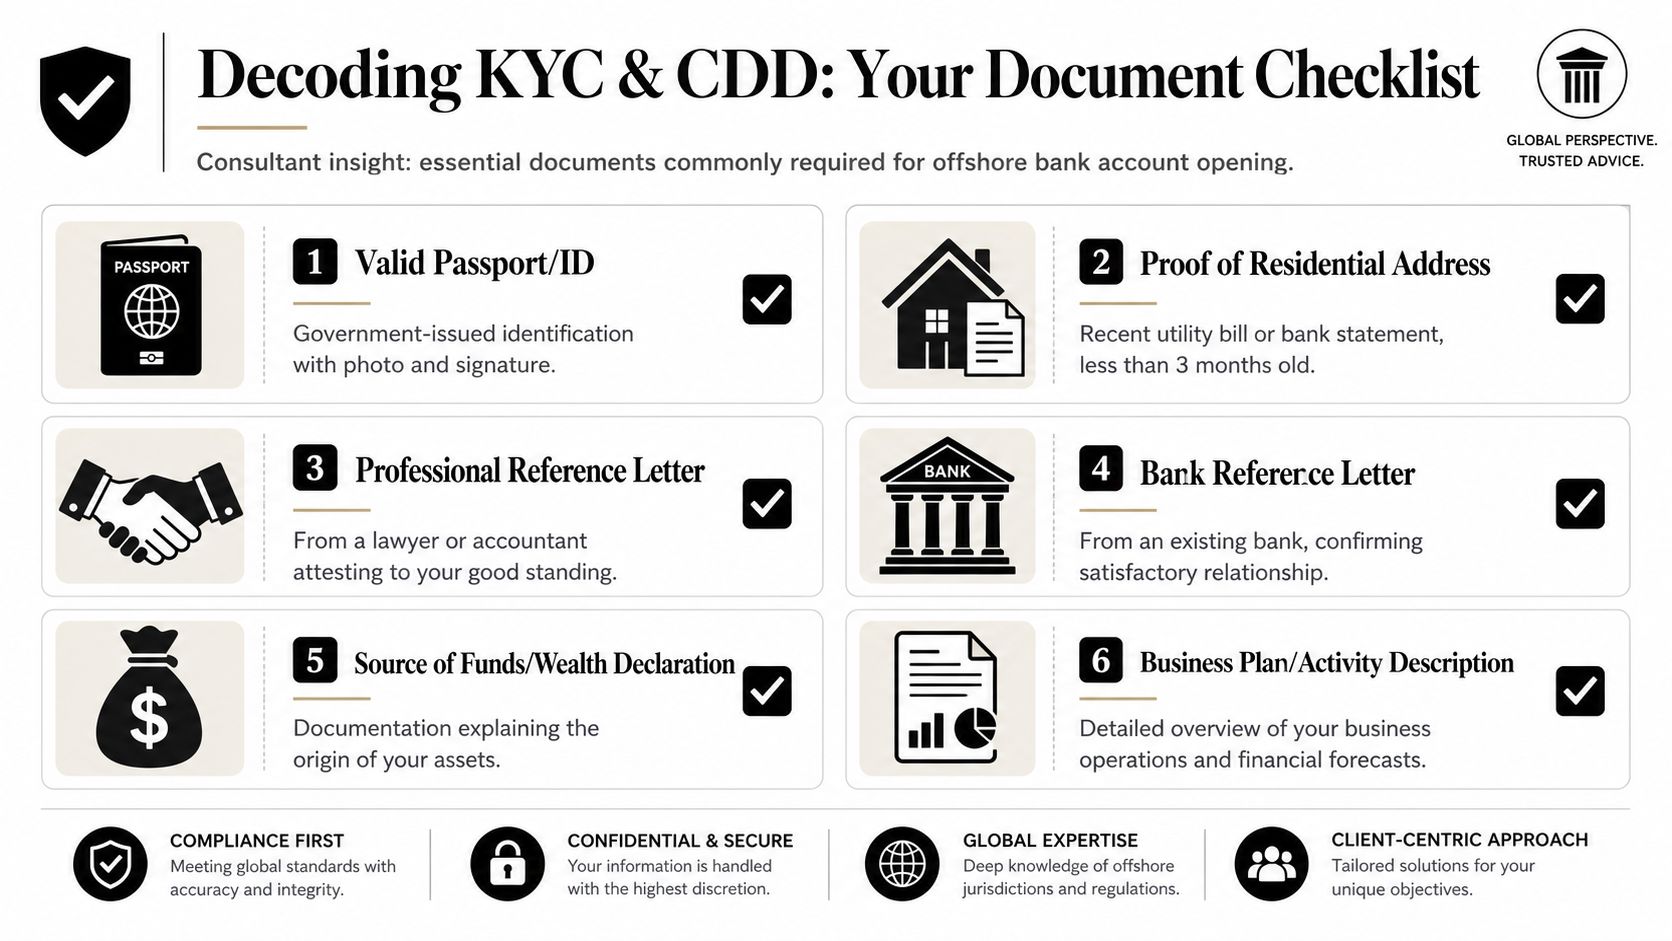
Decoding KYC and CDD Your Document Checklist
Compliance teams don't read your file like a founder reads it. They aren't looking for effort. They're looking for alignment.
That's why a file can feel complete to the applicant and still fail the bank's review. The usual culprit is document inconsistency. Even minor mismatches in addresses or shareholder details across corporate papers and KYC records can trigger delays or refusal, according to Al Arabiya Group's note on offshore bank account rejection risks.
What banks actually compare
A compliance officer will usually review your file horizontally, not vertically. They compare one document against another to see whether the story remains identical throughout.
They'll examine the company documents, then test them against the personal KYC documents of each ultimate beneficial owner. If one file says “Road” and another says “Street”, or one document uses a shortened shareholder name while another uses the full legal name, the file may be pushed back for clarification.
The details that usually create problems include:
- Registered names: passport name, shareholder register name, and resolutions must match.
- Addresses: utility bills, bank statements, and internal forms should present the same residential address format.
- Shareholding logic: the ownership chain must be clear from the operating company to the ultimate beneficial owner.
- Signatory authority: board resolutions and application forms must identify the same authorised persons.
Build one master file
The safest approach is to prepare a single controlled file before submission. That means not just collecting documents, but standardising the data that appears across them.
Send one complete file, not a series of corrections. Every later amendment gives compliance a reason to reopen earlier questions.
For offshore companies, this usually means checking corporate records, KYC forms, and source-of-funds evidence together before anything goes to the bank. If the bank asks for updates later, those updates should fit the same narrative already established in the original pack.
The source-of-funds narrative matters
Many applicants underestimate this part because they assume the bank only wants proof that money is legal. The bank wants more than that. It wants a coherent explanation that connects the owner, the company, and the expected account activity.
A strong narrative usually explains:
- How the owner accumulated funds or wealth
- How those funds relate to the company's business model
- Why the expected transaction flow is commercially normal
- Why the requested UAE banking relationship is appropriate
For non-residents, documentary formalities become stricter. UAE banks may require certified company profiles, board resolutions naming signatories, and audited accounts or written revenue explanations. Foreign nationals can also face delays if documents aren't translated and attested, as outlined in Binderr's guide to business bank account opening in the UAE.
A consultant's pre-submission check
Before any file goes live, I'd pressure-test it with a simple internal review:
- If a compliance officer reads only the first page of each document, does the same ownership story appear every time?
- If they compare the company activity to the source of funds, does the explanation still make sense?
- If they request in-person verification, are the signatories and UBOs ready to support the same narrative verbally?
That's what turns a document pack into a bankable application.
Selecting a Bank and Managing the Timeline
A common failure point appears after the documents are ready. A founder submits the same file to a top-tier bank, a mid-market bank, and a digital provider, then assumes the fastest reply will be the best option. In practice, the first question is simpler. Which institution is built for this exact client profile?
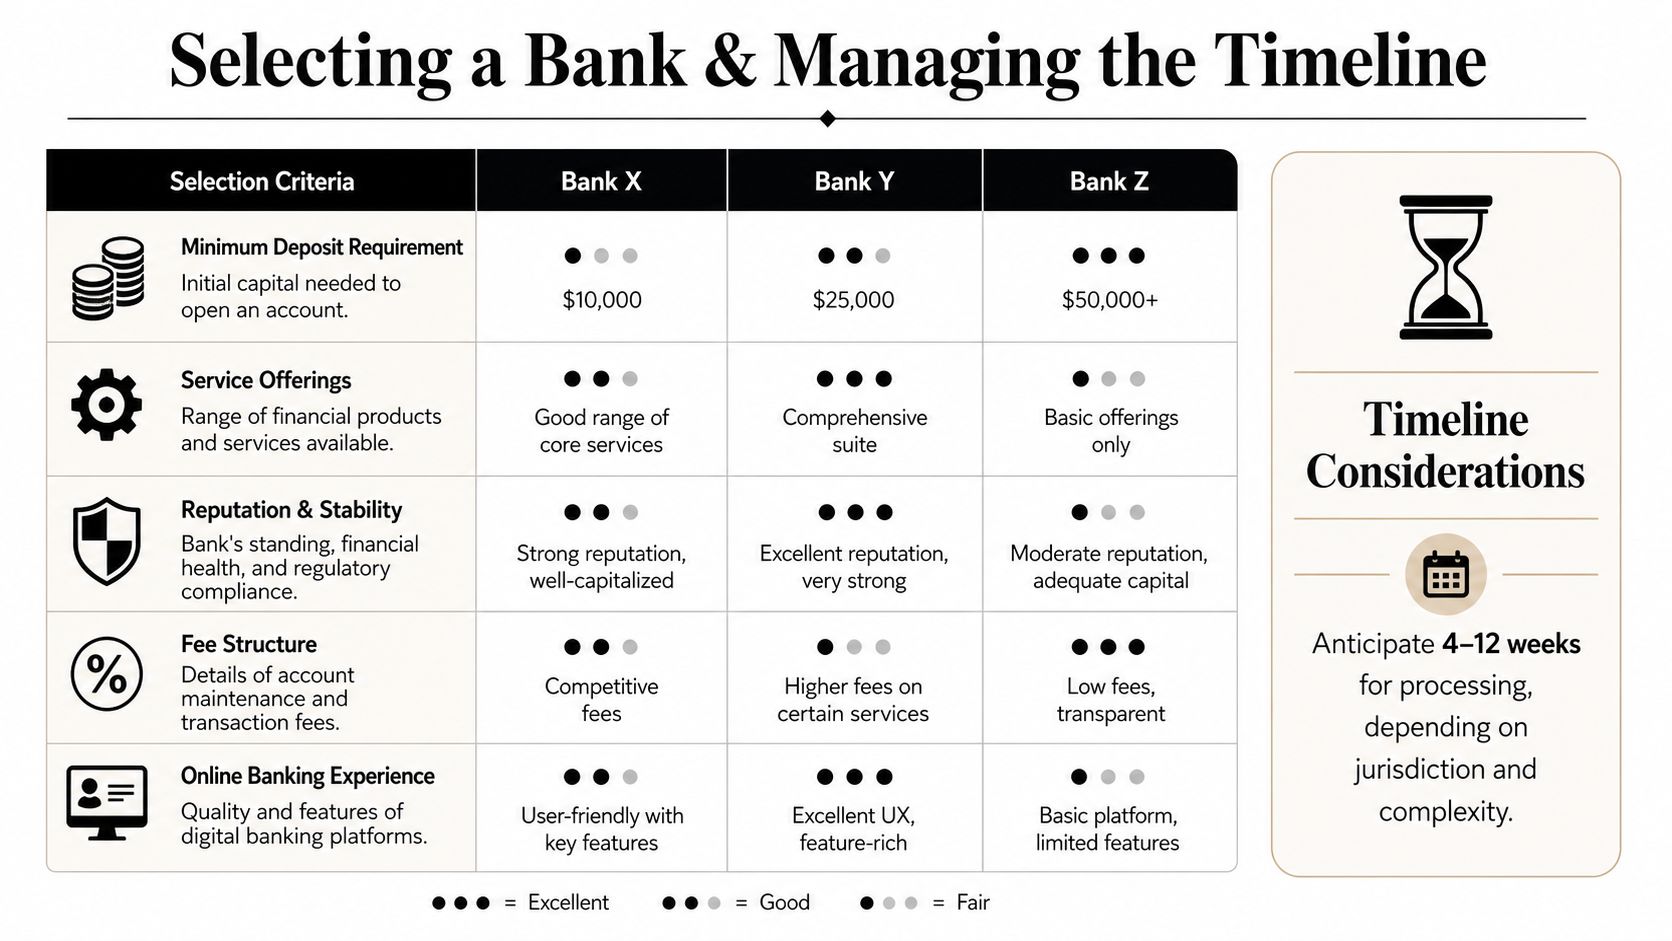
The answer depends less on prestige and more on substance. UAE banks assess offshore companies through a practical lens. Where does the business operate, who controls it, what commercial activity supports the account, and how visible is that activity outside the corporate documents? That is why the old idea of offshore banking as a privacy play causes poor bank selection from the start. Banks are looking for a credible operating story, not a polished logo on the application form.
Traditional banks versus digital options
There are usually two workable routes.
Traditional banks suit companies with a clear commercial footprint, higher balances, and counterparties that expect a conventional banking relationship. Digital banks and EMIs can work well for earlier-stage businesses that need transaction capability first and can live without the full product range of a traditional bank.
The trade-off is practical.
| Option | What tends to work | What often doesn't |
|---|---|---|
| Traditional bank | Established operating history, strong UBO profile, higher balances | Thin activity narrative, unclear ownership, low opening balance |
| Digital bank or EMI | Early-stage operations, simpler payment needs, lower starting capital | Complex treasury needs, expectation of full private banking features |
Minimum balance expectations, onboarding friction, and product depth vary widely from one institution to another. As noted earlier, some banks set the bar much higher than founders expect, especially where the offshore company has limited visible substance. A prior personal banking relationship can help in some cases, but it does not fix a weak corporate profile.
Why the timeline often stretches
Offshore applications usually take longer than standard operating company accounts because the bank is testing more than identity. It is checking whether the structure makes commercial sense and whether the people behind it can support that story consistently if compliance asks follow-up questions.
That review slows down quickly when the bank cannot see real economic substance.
For UAE offshore entities, the friction point is rarely the incorporation documents alone. It is the supporting proof around them. Client contracts, invoices, supplier relationships, office arrangements, group structure charts, and a credible explanation of where management decisions are made often carry more weight than applicants expect. If those pieces arrive late or contradict each other, the file goes into a second review cycle.
I have seen applicants lose weeks by treating the bank submission as an administrative step. It is closer to a risk review.
How to choose realistically
Choose the bank by operating fit.
- If the company is newly formed and mainly needs payment functionality: a digital provider or EMI may be the more realistic starting point.
- If customers or suppliers expect a recognised bank counterparty: a traditional UAE bank may justify the longer process and higher balance expectations.
- If the ownership structure crosses several jurisdictions: use a bank that allows proper pre-screening before a formal submission.
- If the beneficial owners are non-resident: expect closer testing of business presence, transaction rationale, and signatory availability.
A realistic plan also includes time for clarification requests, not just initial submission. Strong files still get questions. Weak files get silence, then rejection.
Smart Classic Business Hub supports clients at this stage by shortlisting banks that match the ownership profile, business model, and expected account activity, then preparing the file for the review standard UAE compliance teams apply.
Avoiding Rejection Common Pitfalls and Compliance Risks
The biggest misconception in offshore banking is also the one that causes the worst planning errors. Some applicants still believe “offshore” means private in the old sense of the word. In the UAE, that assumption is wrong.
The UAE is a transparent jurisdiction that participates in the Common Reporting Standard and enforces AML controls. For ordinary businesses, anonymous offshore accounts don't exist, and banks share beneficial ownership data with foreign tax authorities, as explained in Velmont Crest's analysis of the offshore banking secrecy myth in Dubai.
The anonymity myth still damages applications
When a client approaches banking as if secrecy is the objective, the problem shows up in the file. They become vague about ownership, hesitant about tax residence, or evasive about the commercial purpose of the account. Compliance teams read that behaviour as risk.
A cleaner approach is the opposite. Be explicit about ownership, clear about tax obligations in the relevant jurisdictions, and direct about how the account will be used. Banks don't expect perfection. They expect transparency.
Non-resident founders face stricter practical checks
Another avoidable problem is treating remote opening as a default right. Some offshore clients can progress a long way remotely, but non-resident beneficial owners often still face in-person verification requirements at the final stage. If that possibility isn't planned in advance, the file stalls.
Common failure points include:
- Loose translations: foreign-language documents submitted without proper translation
- Weak attestation: documents that are technically available but not in a form the bank accepts
- Unprepared meetings: signatories who can't clearly explain the business model during KYC review
- Generic activity descriptions: language that sounds copied from a template rather than tied to real trade
A compliant offshore structure is not secret. It is documented, defensible, and easy to explain.
Rejection usually starts before the rejection email
Most refusals don't begin with a formal decline. They begin with silence, repeated clarifications, and requests for “one final document” that never ends the cycle. By then, the file has already been marked as difficult.
The way to avoid that outcome is simple in principle and demanding in practice. Submit a coherent file, choose a bank whose appetite matches the profile, and prepare every owner and signatory to support the same factual narrative verbally and in writing.
Exploring Alternatives to Traditional Offshore Accounts
A traditional offshore bank account isn't always the right first move. Sometimes the company is newly formed, the activity is legitimate but early-stage, or the founder needs operational payment capability while a full banking application is still under review.
That's where payment service providers, multi-currency business accounts, and certain EMI-style platforms can play a useful role. They aren't interchangeable with a full bank account, but they can solve real problems if used deliberately.
Where alternatives make sense
These platforms can work well when a business needs to invoice in multiple currencies, collect customer payments, or pay international suppliers without waiting for a traditional offshore account to go live.
Their practical advantages usually include:
- Faster onboarding: useful when timing matters and the business can't pause operations
- Lower entry barriers: often better suited to founders who don't want to lock up large balances at the start
- Operational simplicity: strong for payment collection, online access, and basic treasury movement
For many companies, the right strategy isn't either-or. It's sequencing. Use an alternative platform for early operations, then move into a traditional banking relationship once the business has stronger transaction history and a fuller compliance record.
Where alternatives fall short
These tools also have limits, and founders should understand them clearly.
A payment platform may not offer the same comfort to counterparties that expect a conventional bank relationship. Some providers are excellent for collections and payouts but less suitable for holding larger reserves, supporting more complex compliance requests, or matching the service model of a conventional corporate bank.
A sensible decision comes down to use case. If the business needs payment rails and working flexibility, an alternative can be practical. If it needs a full banking relationship for higher-trust counterparties, broader facilities, or long-term treasury structure, traditional banking still matters.
Think in layers, not labels
The smartest founders build financial infrastructure in layers. One account or platform handles operating collections. Another supports supplier payments. A more conventional bank relationship anchors the longer-term structure.
That approach reduces pressure on a single application and gives the company continuity while a more formal offshore banking relationship is being built carefully.
Your Partner in UAE Banking How We Can Help
A founder sets up an offshore company expecting privacy and fast onboarding, then meets the first real obstacle. The bank asks for proof of business activity, source of funds, ownership clarity, and a credible reason for banking in the UAE. That is the point where offshore banking stops being a paperwork exercise and becomes a substance exercise.
For UAE banks, a strong application is not built around anonymity. It is built around consistency. The company structure, business model, ownership trail, transaction profile, and economic substance all need to fit together without gaps. If one part looks engineered only for account opening, compliance will usually find it.
What practical support should look like
Good support starts before the application goes to a bank. We review the file the way a compliance team is likely to review it, with attention to the points that trigger delay or rejection.
That usually means pressure-testing five areas:
- whether the offshore entity is the right vehicle for the intended transactions
- whether the activity description reflects a real operating business rather than a generic label
- whether UBO, shareholder, and signatory records match across all documents
- whether the source-of-funds and expected account activity are clear, proportionate, and evidenced
- whether the client has enough economic substance to satisfy the bank's risk view
In practice, economic substance is where many applications weaken. A bank may ask where management decisions are made, who the counterparties are, why the UAE account is needed, and what commercial footprint supports the structure. Generic guides often underplay this. Banks do not.
Where founders save time and reduce risk
The biggest delay usually comes from a weak first file. Once an application starts generating follow-up questions, the bank is no longer reviewing a clean submission. It is reviewing corrections, explanations, and inconsistencies.
We see the same pattern often. A founder incorporates first, chooses the bank later, and only then starts assembling the compliance narrative. That order creates friction. A better approach is to test bankability before submission, identify any substance gaps early, and decide whether the business is ready for a conventional offshore account now or should build more operating history first.
That judgment matters.
Some clients are ready to apply immediately. Others are better served by tightening their documentation, clarifying their commercial model, or waiting until the business can show stronger counterparties, invoices, contracts, or management presence. The right outcome is not the fastest approval on paper. It is an account structure the business can keep, use, and defend under ongoing review.
Smart Classic Business Hub helps clients assess banking readiness, organise a compliant document file, and align company setup with what UAE banks ask for during onboarding.